
Back
    Residential Dallas–Fort Worth, TX May 2026

    Multifamily Acquisition: Twelve-Unit Apartment Property, Dallas–Fort Worth

    An acquisition profile examining a privately owned twelve-unit DFW property with strong occupancy but incomplete financial reporting, and the methodology used to reconstruct a credible operating picture.

    This acquisition profile examines asset strategy, underwriting method, transaction structure, and value-creation considerations. Counterparty and pricing details are not disclosed.

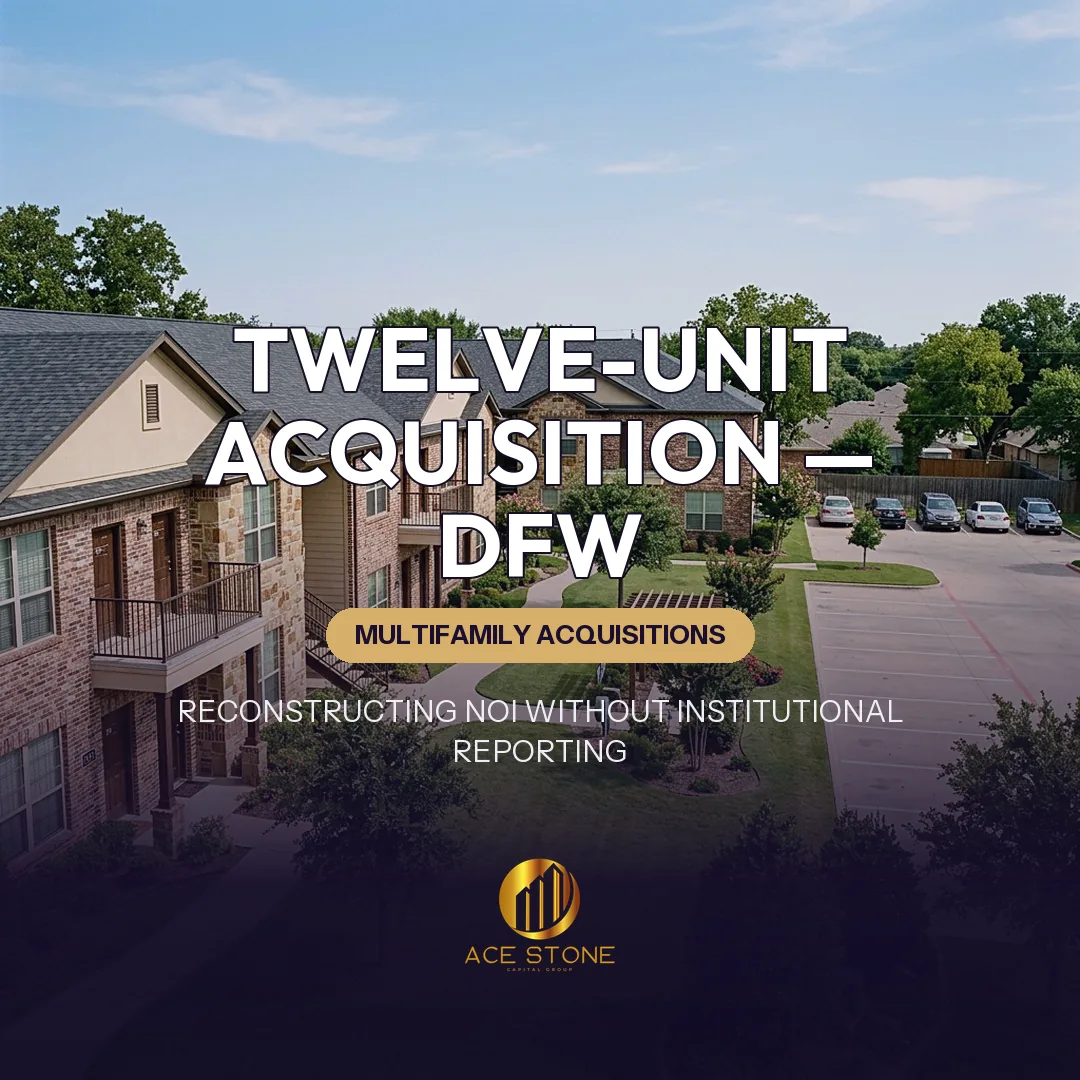
    Texas garden-style twelve-unit apartment property with central courtyard.
    Representative imagery of the asset type and market — not a photograph of the subject property.

    Case Context

    This acquisition profile examines a privately owned twelve-unit apartment property in the Dallas–Fort Worth metroplex with strong occupancy and incomplete historical financial reporting. It sets out AceStone Capital Group's underwriting methodology; specific counterparties and pricing are not identified.

    Property Profile

    A twelve-unit garden-style property typically comprises one or more two-story buildings arranged around surface parking or a central landscaped area, with individually metered units, a shared water and sewer service, and a common exterior maintenance obligation. At this size the asset is operationally institutional but frequently owned and managed privately, which is precisely the mismatch that creates the reporting gap in this profile.

    Applied exampleSee how this played out in Cash Offers vs. Traditional Listings: What Sellers Should Know — a residential acquisition in National.

    The Reporting Gap

    Incomplete reporting rarely means dishonest reporting. It usually means an owner tracked deposits and paid bills without producing period statements, allocated personal and property expenses loosely, and performed maintenance labor without invoicing it. The buyer's task is not to accept or reject the seller's figures but to rebuild the operating picture from sources that do not depend on them.

    Rent Roll and Collections Verification

    The rent roll is verified against executed leases unit by unit, then against the deposit record for the trailing period available, then against tenant estoppels where the seller permits contact. Where all three agree, the income line is established. Where they diverge, the lowest corroborated figure is used. Occupancy strength does not substitute for this reconciliation; a building can be full and still under-collect.

    Applied exampleSee how this played out in Why Out-of-State Owners Sell to Direct Buyers — a residential acquisition in Multi-State.

    Reconstructing Expenses

    Expenses are rebuilt from primary documents rather than from statements: county tax records, utility account histories for master-metered services, the insurance declaration page, service contracts for landscaping, pest and trash, and any available invoices for repairs. Where a category cannot be documented, it is underwritten to a market benchmark for comparable DFW product, and the benchmark is disclosed as an assumption rather than presented as history.

    Normalizing to Professional Operation

    Even a fully documented owner-operated expense base understates the cost of professional operation. Normalization adds market management, a maintenance and turnover allowance calibrated to unit age and turnover frequency, per-unit reserves, and administrative cost. Property tax is re-underwritten on a post-transfer basis, which in this market is frequently the single largest adjustment to the seller's figures.

    Applied exampleSee how this played out in Why Infill Lots Are Outperforming in Growth Corridors — a residential acquisition in U.S. Growth Markets.

    Rebuilding Net Operating Income

    Net operating income is reconstructed as verified collections less normalized expenses, with an economic vacancy factor that reflects observed turnover rather than the point-in-time physical occupancy. The result is typically below the seller's presented figure. That difference is not a negotiating position; it is the consequence of pricing costs the prior owner absorbed personally and taxes that reset on transfer.

    Verification Methodology

    The governing principle is independence of sources. Any single document can be incomplete; three independent records rarely fail in the same direction. Leases, deposits and estoppels triangulate income. Tax records, utility histories and insurance declarations triangulate expense. Physical inspection triangulates the maintenance narrative. Items surviving all three checks are underwritten; items that do not are treated as risk.

    Basis and Structure

    Basis is set from reconstructed net operating income, cross-checked against comparable twelve-unit sales and replacement cost, and reduced by any capital schedule identified in inspection. Structure favors a defined diligence window in which verification is completed, an as-is purchase without post-inspection renegotiation, and a fixed closing date — terms that are valuable to a private owner and are priced accordingly.

    Risk Factors

    The material risks are unverifiable income components, deposit liabilities not properly held, deferred maintenance masked by continuous occupancy, post-transfer tax reassessment, expense benchmarks proving optimistic under professional management, and rent assumptions exposed to new supply in a metroplex with active construction.

    Key Takeaway

    Disciplined underwriting can establish a credible operating picture for a privately managed asset that lacks institutional-quality reporting — but only by rebuilding the picture from independent primary evidence rather than adjusting the seller's summary. Owners of comparable assets can review parameters on the multifamily acquisitions desk.

    Conclusion

    Reporting quality is a diligence variable, not a value variable. The framework above reflects AceStone Capital Group's underwriting posture on assets of this profile.

    What This Case Shows

    A structured example of how AceStone Capital Group sources, underwrites, and structures off-market residential acquisitions in Dallas–Fort Worth, TX. For broader context, see our active acquisition markets or initiate a direct-sale review for a similar property.

    Have a Property to Sell?

    Receive a written offer or a clear pass within 1–2 business days.

    Request a Cash Offer