
Back
    Residential Dallas–Fort Worth, TX January 2026

    Residential Portfolio Acquisition: Eight Single-Family Rentals, Dallas–Fort Worth

    A analysis of how eight scattered rental homes under one owner would be underwritten as a single coordinated Dallas–Fort Worth acquisition.

    This acquisition profile examines asset strategy, underwriting method, transaction structure, and value-creation considerations. Counterparty and pricing details are not disclosed.

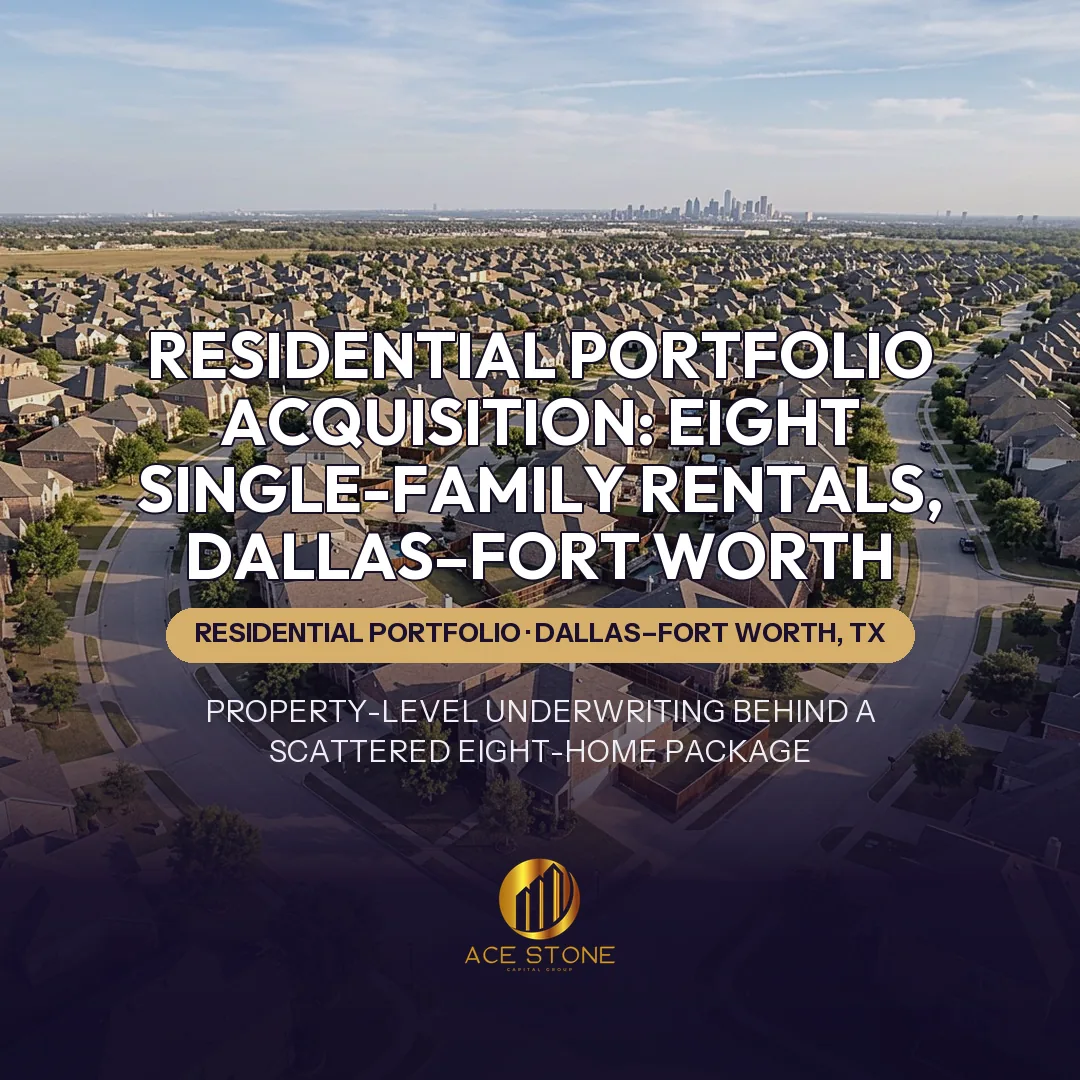
    Aerial view of a Dallas–Fort Worth suburban neighborhood with scattered single-family rental homes.
    Representative imagery of the asset type and market — not a photograph of the subject property.

    Case Context

    This acquisition profile examines how AceStone Capital Group evaluates a fragmented single-family rental portfolio. Specific counterparties and pricing are not identified. The subject profile is an owner holding eight rental homes across four Dallas–Fort Worth submarkets, assembled opportunistically over roughly fifteen years rather than acquired as a designed portfolio.

    Ownership Situation

    Fragmented portfolios typically arise from sequential purchases rather than a single strategy. The homes differ in vintage, floor plan, lot size, and submarket. Management may have been self-performed for part of the hold and outsourced later, leaving inconsistent lease documentation, mixed renewal practices, and uneven maintenance records. An owner in this position is usually motivated by management fatigue, estate planning, or a desire to convert scattered equity into a single liquidity event rather than by asset-level distress.

    Applied exampleSee how this played out in Cash Offers vs. Traditional Listings: What Sellers Should Know — a residential acquisition in National.

    Portfolio Characteristics

    A dispersed eight-home portfolio in this metro would typically span multiple school districts, two or more counties, and materially different tax jurisdictions. Dispersion of this kind reduces single-neighborhood demand exposure but raises per-property management cost, travel time for maintenance, and the number of independent title chains that must be cleared before a coordinated closing is achievable.

    Property-Level Underwriting

    Each home is underwritten as its own asset before any portfolio number is formed. The property-level file includes in-place rent against submarket comparables, lease term and expiration, payment history at a summary level, occupancy status, roof and mechanical age, foundation condition typical of North Texas expansive-clay soils, county assessed value and protest history, insurance premium and deductible structure, and a scoped deferred-maintenance budget. Two of eight homes carrying disproportionate capital needs will change the portfolio conclusion even when the aggregate rent roll appears healthy.

    Applied exampleSee how this played out in Why Out-of-State Owners Sell to Direct Buyers — a residential acquisition in Multi-State.

    Portfolio-Level Analysis

    Portfolio-level work aggregates the property files and then tests them for distortion. Blended rent, blended occupancy, and blended expense ratios are only meaningful once outliers are isolated: a single over-rented home, a single long-vacant home, or a single asset with an unresolved structural item can move a blended figure enough to mask the true economics. Portfolio basis is therefore constructed bottom-up from eight independent valuations, then adjusted for coordinated execution rather than derived top-down from a seller's summary schedule.

    Title and Diligence Coordination

    Eight parcels mean eight title commitments, eight lien searches, and potentially several different vesting structures if homes were purchased under different entities or before a marital or estate event. Diligence is sequenced so that title curative begins immediately at the portfolio level while physical inspection is batched geographically to minimize tenant disturbance and access scheduling across occupied units.

    Applied exampleSee how this played out in Why Infill Lots Are Outperforming in Growth Corridors — a residential acquisition in U.S. Growth Markets.

    Risks Identified

    The principal risks in this profile are documentation asymmetry between well-managed and poorly managed assets, concentration of capital need in a minority of the homes, tax reassessment following transfer, insurance repricing across an aged roof cohort, and the execution risk of an all-or-nothing close where one uncleared title chain can delay seven otherwise ready parcels.

    Execution Considerations

    A coordinated structure would contemplate one agreement, one escrow, and one funding date, with a defined mechanism for handling a parcel that cannot be cleared in time — either repricing at the portfolio level or carving the parcel out on pre-agreed terms. Sellers value the single-event exit; disciplined buyers preserve the right to reprice rather than remove assets, so that the remaining basis is not silently degraded.

    Key Takeaway

    A portfolio acquisition still requires property-level underwriting. Weak individual assets can materially distort an attractive aggregate presentation, and the discipline of pricing each home independently before blending is what protects the portfolio basis.

    Conclusion

    Fragmented rental portfolios can be genuinely efficient exits for owners and sound acquisitions for buyers, but only where the analysis resolves to the individual asset. The framework above reflects AceStone Capital Group's underwriting posture on assets of this profile.

    What This Case Shows

    A structured example of how AceStone Capital Group sources, underwrites, and structures off-market residential acquisitions in Dallas–Fort Worth, TX. For broader context, see our active acquisition markets or initiate a direct-sale review for a similar property.

    Have a Property to Sell?

    Receive a written offer or a clear pass within 1–2 business days.

    Request a Cash Offer