
Back
    Residential Brooklyn, NY August 2026

    Residential-Over-Retail Acquisition: Underwriting a Six-Unit Mixed-Use Building in Brooklyn

    A three-story Brooklyn building — six apartments over two storefronts — underwritten as two separate income streams rather than one blended cap rate.

    This acquisition profile examines asset strategy, underwriting method, transaction structure, and value-creation considerations. Counterparty and pricing details are not disclosed.

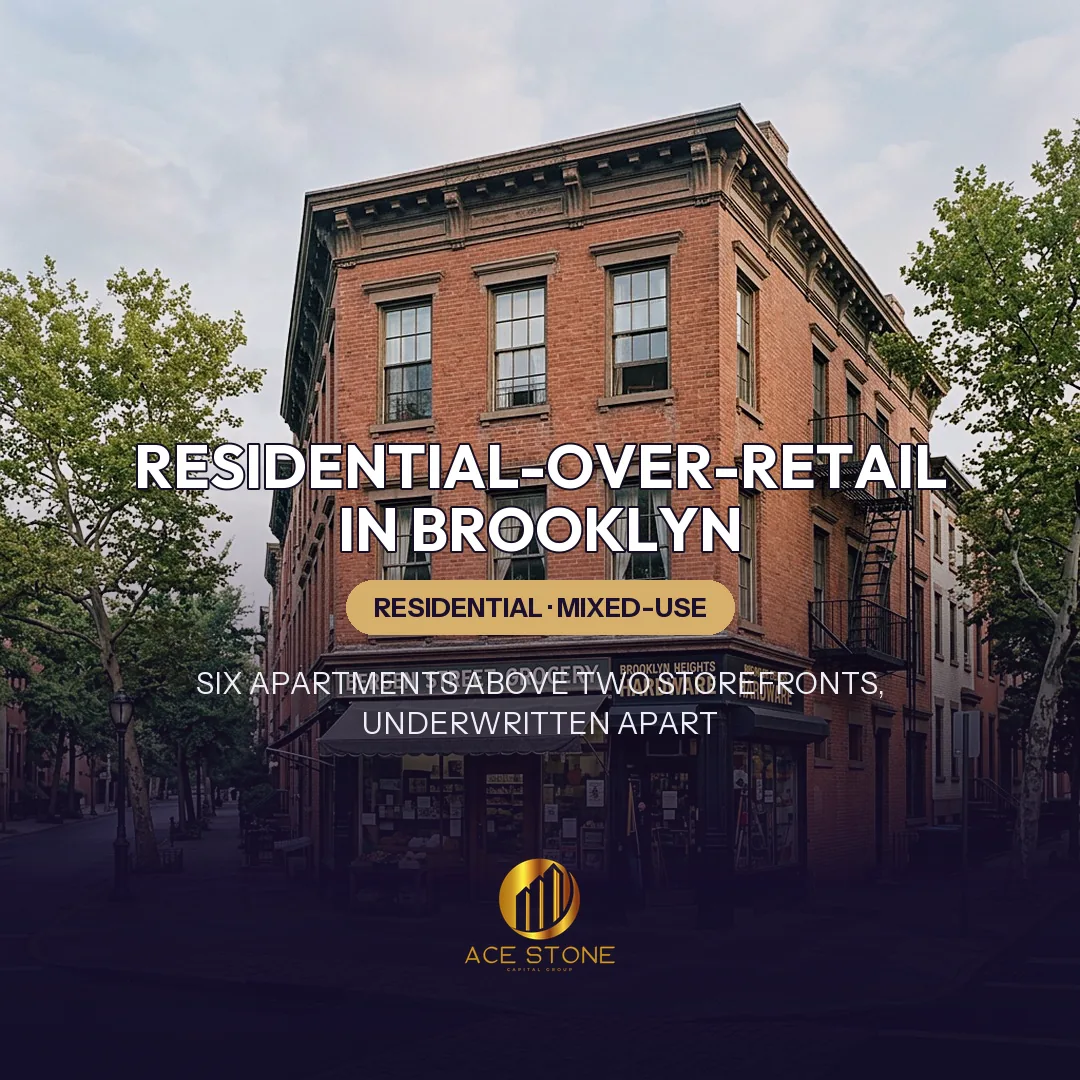
    Classic three-story Brooklyn corner mixed-use building with neighborhood storefronts at street level and apartments above.
    Representative imagery of the asset type and market — not a photograph of the subject property.

    Executive Summary

    The subject is a three-story corner building: six apartments on the upper floors and two ground-floor retail bays. Gross income splits roughly seventy-thirty in favour of the apartments, which is precisely why the property is priced as a residential asset by most bidders. Our position is that the storefront income cannot be capitalized at the residential rate, because its volatility, downtime and re-tenanting cost profile are entirely different. Separating the streams moves the supportable price meaningfully below the asking basis without changing a single assumption about the neighbourhood.

    Case Context

    This is a Acquisition profile. Specific properties, counterparties, and pricing are not identified. The profile is drawn from conditions common across Brooklyn's older commercial corridors: pre-war construction, a residential entry on the side street, retail frontage on the avenue, and a rent roll that has drifted away from market in both directions — apartments below, storefronts above.

    Applied exampleSee how this played out in Why Infill Lots Are Outperforming in Growth Corridors — a residential acquisition in U.S. Growth Markets.

    Property Profile

    Three stories over a partial cellar. Six residential units — a mix of one-bedroom and two-bedroom layouts of roughly 600 to 850 square feet — reached by a single stair. Two retail bays at grade, one corner space with wraparound glazing and one shallower interior space. No parking. Steam or hydronic heat from a single boiler, individual electric metering for apartments, a separately metered commercial service, and a roof at or past the midpoint of its expected life. Building systems, not layout, drive the capital plan.

    Residential Component

    The apartments are the reliable part of the asset. Turnover is frequent but small, re-leasing is measured in weeks, and demand does not depend on any single employer or retail category. In-place rents sit below achievable rents for renovated comparable units nearby, but the gap is not free money: capturing it requires vacancy, a scoped unit renovation, downtime and marketing. Where units are smaller than newer competing product, we assume a discount to that comparable set rather than parity, whatever the finish level.

    Applied exampleSee how this played out in The Migration Effect: How Population Shifts Drive Lot Demand — a residential acquisition in U.S. Growth Markets.

    Commercial Component

    Two bays mean concentration. The loss of one storefront removes half the commercial income and can leave a dark window on the corner for two or three quarters. We abstract each lease before touching the rent roll: commencement and expiry, base rent and escalations, recovery method for taxes and insurance, renewal options and their strike rents, exclusive-use clauses, assignment rights, deposits and any unamortized landlord work. A below-market renewal option is a value reduction even when today's rent looks fine, because the buyer purchases the option along with the space.

    Rent Roll and Rollover

    The rent roll is rebuilt from leases and bank deposits, not from the offering summary. Each residential tenancy is coded by lease status, concession history and payment record; each retail tenancy is placed on a rollover timeline. Every commercial expiration inside the hold period carries an assumed downtime, a tenant-improvement allowance and a leasing commission. Residential rollover carries a per-turn cost and a short vacancy factor. Nothing is assumed to renew simply because it has renewed before.

    Applied exampleSee how this played out in Path-of-Growth Markets: Where Land Appreciation Starts Early — a residential acquisition in U.S. Growth Markets.

    Operating Expenses

    Expenses are rebuilt rather than adopted. Property taxes are restated on a post-sale assessment, not the seller's long-held basis. Insurance is quoted for combined residential and commercial occupancy, which prices differently than a purely residential policy. Water and sewer, common electricity, heating fuel, trash, snow and sidewalk obligations, repairs, and management at a market rate for a hybrid asset are all included, along with a per-unit replacement reserve and a separate reserve for storefront systems the landlord owns.

    NOI Normalization

    Two normalized net operating income figures are produced, not one. Owner-performed management and maintenance are replaced with market-rate line items. Non-recurring income and expense items are removed. Vacancy and credit loss are applied separately: a residential factor consistent with the submarket, and a commercial factor that reflects the actual lease structure and tenant credit. The blended figure is calculated only for presentation; it is never the figure that sets price.

    Acquisition Basis

    Value is built by capitalizing the residential net income at the rate the local apartment market supports, capitalizing the retail net income at a wider rate that reflects re-tenanting risk and downtime, then subtracting near-term capital: roof, boiler, façade and sidewalk work, plus the renovation budget for units expected to turn in the first two years. The sum is the maximum price at which the underwriting still holds. It is usually below the price produced by a single blended rate, and the difference is the value of the discipline.

    Downside Scenarios

    Three cases are modelled. Conservative assumes one storefront goes dark for three quarters, retail re-lets ten to fifteen percent below the current rate, and residential upside arrives one year slower than planned. Base assumes retail holds at market with normal downtime and residential turns capture most of the achievable premium. Upside assumes both bays renew at market with no downtime. The acquisition price is set against the conservative case, not the base case; the base case is what makes the return acceptable rather than what makes the deal possible.

    Exit Positioning

    The likely buyer at exit is a local owner-operator or a small fund that treats the asset as an apartment building with an income kicker. That buyer will apply the same separation of streams, which means exit pricing is far more sensitive to the state of the retail leases at sale than to their state at purchase. Selling with newly signed, market-rate storefront leases and stabilized apartments is a materially different transaction than selling into a rollover window.

    Key Takeaways

    Residential stability can absorb some storefront volatility, but it cannot be used to disguise it. Underwrite each stream on its own terms, price each at its own rate, reserve separately for each, and let the combined number be an output rather than an input. Owners weighing a sale of a comparable building can review our approach on the residential property acquisitions page, or start a confidential review through the offer request process.

    What This Case Shows

    A structured example of how AceStone Capital Group sources, underwrites, and structures off-market residential acquisitions in Brooklyn, NY. For broader context, see our active acquisition markets or initiate a direct-sale review for a similar property.

    Have a Property to Sell?

    Receive a written offer or a clear pass within 1–2 business days.

    Request a Cash Offer