
Back
    Residential Austin, TX June 2026

    Duplex Acquisition: Infill Basis in Austin's Urban Core

    A analysis of an Austin infill duplex holding both current-income value and embedded land optionality, and why the buyer should not pay today for an unproven future scenario.

    This acquisition profile examines asset strategy, underwriting method, transaction structure, and value-creation considerations. Counterparty and pricing details are not disclosed.

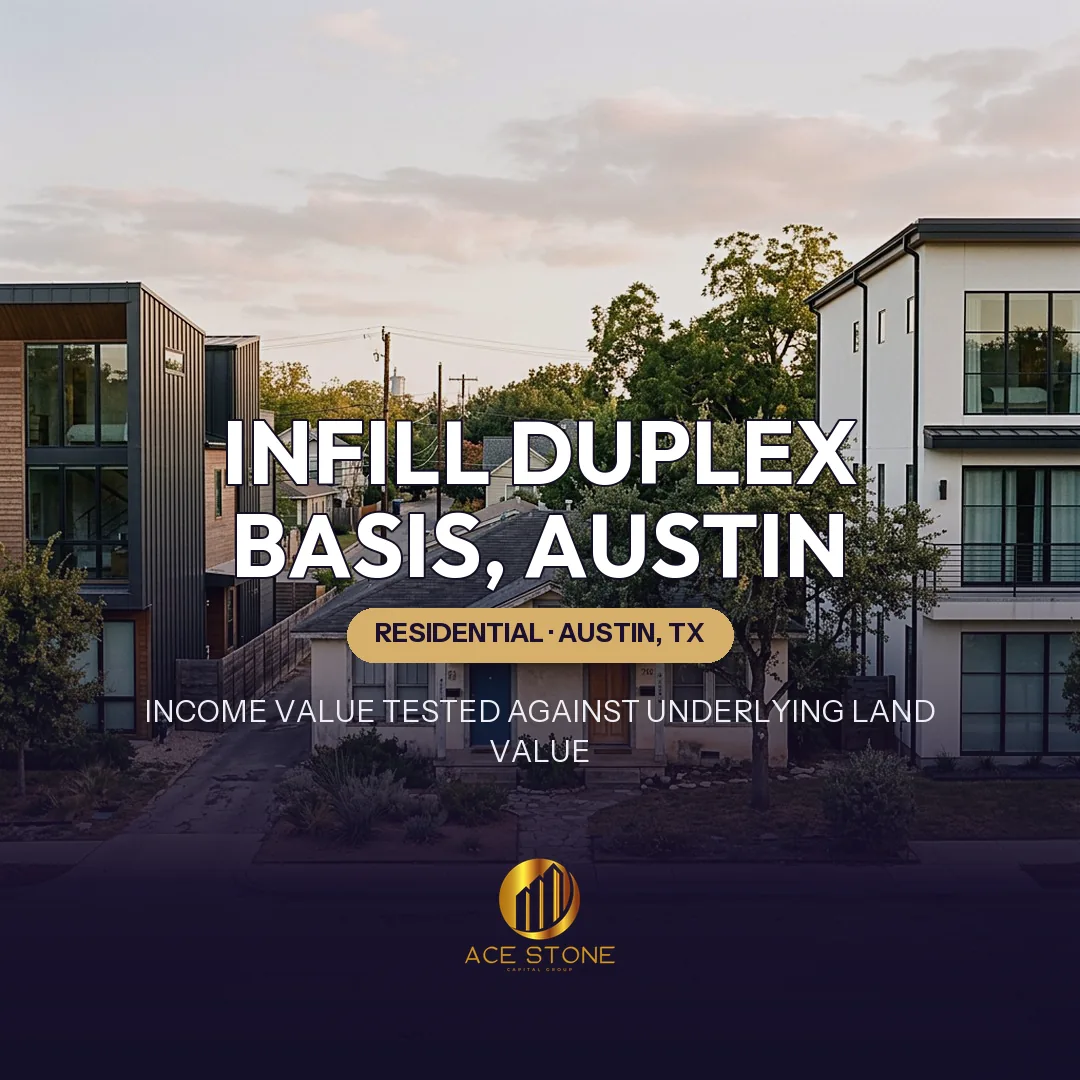
    Older duplex surrounded by newer infill construction in central Austin.
    Representative imagery of the asset type and market — not a photograph of the subject property.

    Case Context

    This acquisition profile examines an older two-unit property in an appreciating infill corridor of Austin's urban core. It sets out AceStone Capital Group's underwriting methodology; specific counterparties and pricing are not identified.

    Acquisition Profile

    An infill duplex sits at the intersection of two valuation frameworks. As an operating asset it is worth the capitalized value of its rental income. As a parcel it is worth what the underlying land will support under current entitlement, less demolition. In corridors experiencing sustained redevelopment, the second figure can approach or exceed the first, and the discipline lies in deciding which one the buyer is actually purchasing.

    Applied exampleSee how this played out in Why Infill Lots Are Outperforming in Growth Corridors — a residential acquisition in U.S. Growth Markets.

    Current Income Analysis

    The income case is built conventionally: leases, in-place rent against submarket comparables, expiration schedule, operating expenses re-underwritten to post-transfer conditions including Travis County tax and insurance, and a make-ready reserve appropriate to the building's age. Older infill product frequently carries below-market rent and above-market maintenance, which compresses net income relative to what the gross rent roll suggests.

    Underlying Land Basis

    The land analysis establishes lot dimensions and area, current zoning designation, permitted density and use, setback and impervious cover constraints, height limits, tree preservation obligations, floodplain or creek buffer exposure, and any overlay or neighbourhood plan condition affecting what could be built. Land value is then derived from arm's-length sales of comparable parcels in the same corridor, adjusted for those constraints.

    Applied exampleSee how this played out in The Migration Effect: How Population Shifts Drive Lot Demand — a residential acquisition in U.S. Growth Markets.

    Replacement Cost and Comparable Sales

    Two additional reference points frame the valuation. Replacement cost establishes what it would cost to deliver equivalent space new, which sets an upper bound on what an existing older building can rationally command. Comparable residential and small-multifamily sales in the corridor establish what the market has actually paid for similar improved parcels, which captures how much redevelopment expectation is already embedded in local pricing.

    Redevelopment Optionality

    Optionality is real but conditional. Realising it would require entitlement confirmation, design, permitting, demolition, construction financing, and delivery into a future market, each of which carries cost, time, and uncertainty. The correct treatment is to acknowledge the option as downside protection — the parcel retains residual value independent of the building — without capitalizing a redevelopment outcome that has not been entitled, costed, or committed to.

    Applied exampleSee how this played out in Path-of-Growth Markets: Where Land Appreciation Starts Early — a residential acquisition in U.S. Growth Markets.

    Basis Analysis

    Basis is set at the income value of the operating asset, tested against the land value net of demolition to confirm the buyer is not paying above the parcel's standalone worth. Where land value materially exceeds income value, the asset is a land position with interim income and should be underwritten as such, including the carry cost of holding it. Where income value exceeds land value, it is a rental asset with a floor beneath it.

    Risk Factors

    The material risks are paying a redevelopment premium that never converts, entitlement or code changes altering what the parcel supports, rising tax assessment tracking land appreciation rather than rental income, construction cost inflation eroding future feasibility, and deferred capital in an older building whose owner reasonably declined to invest in a structure with a finite remaining life.

    Key Decision Points

    The decision turns on which valuation the price reflects. A buyer underwriting income and receiving land optionality has acquired protection; a buyer underwriting land and receiving income has acquired a carry-funded option. A buyer paying for both at once has acquired neither margin nor protection.

    Key Takeaway

    A duplex in an infill market can carry both current-income value and embedded land optionality, but the buyer should not pay today for an unproven future scenario. The option is a floor, not a price.

    Conclusion

    Infill two-unit properties reward buyers who price the asset they can operate and treat the land as protection rather than justification. The analysis above reflects AceStone Capital Group's approach. Specific properties, counterparties, and pricing are not identified.

    What This Case Shows

    A structured example of how AceStone Capital Group sources, underwrites, and structures off-market residential acquisitions in Austin, TX. For broader context, see our active acquisition markets or initiate a direct-sale review for a similar property.

    Have a Property to Sell?

    Receive a written offer or a clear pass within 1–2 business days.

    Request a Cash Offer