
Back
    Residential Phoenix, AZ April 2026

    Duplex Acquisition: Mixed-Occupancy Two-Unit Asset, Phoenix

    An acquisition profile examining a Phoenix duplex with one occupied and one vacant unit, and how two occupancy states inside one building create two distinct economic profiles.

    This acquisition profile examines asset strategy, underwriting method, transaction structure, and value-creation considerations. Counterparty and pricing details are not disclosed.

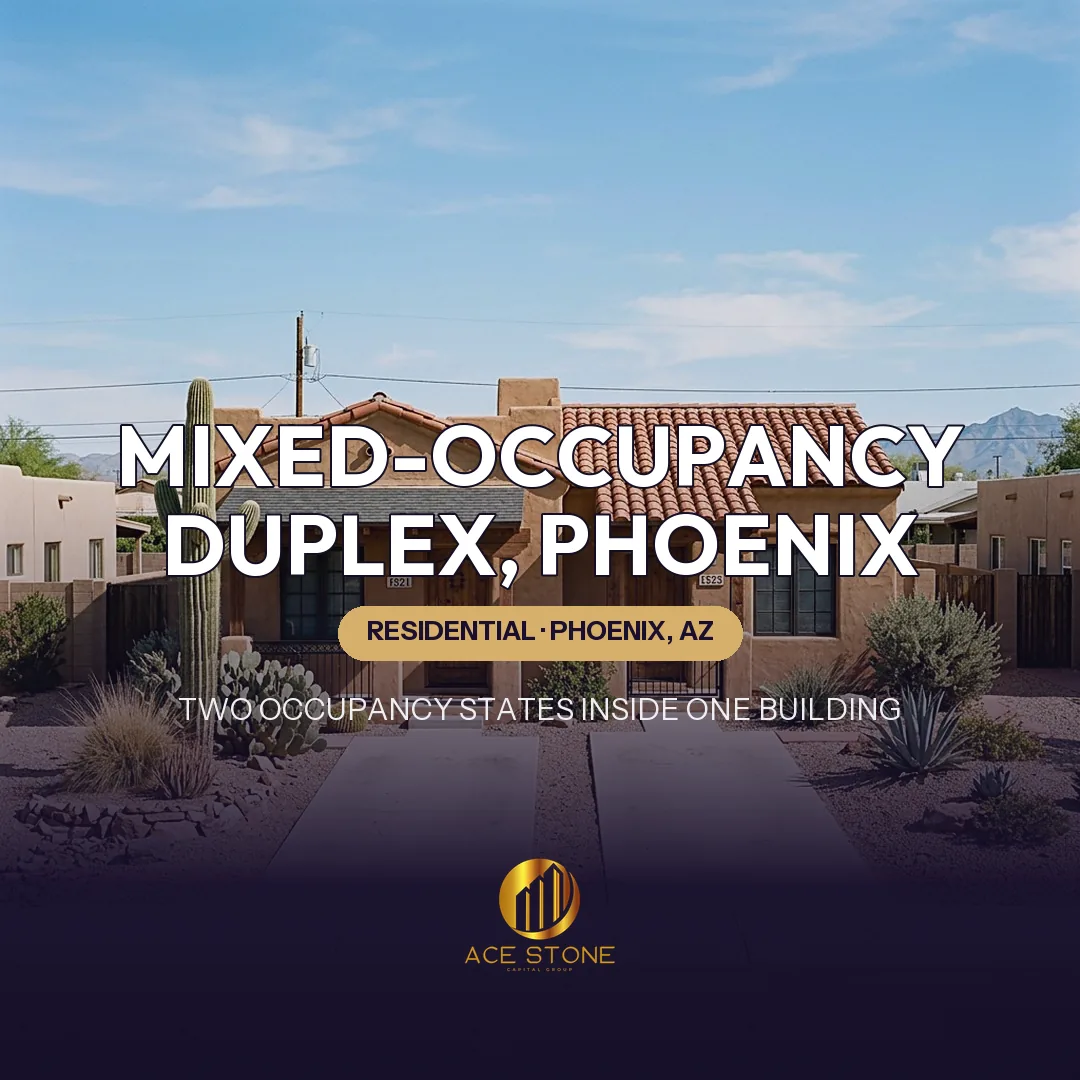
    Southwestern-style duplex with two distinct entrances and driveways in Phoenix.
    Representative imagery of the asset type and market — not a photograph of the subject property.

    Case Context

    This acquisition profile examines a two-unit property in the Phoenix metropolitan area in which one unit is tenant-occupied under an existing lease and the second is vacant. It sets out AceStone Capital Group's underwriting methodology; specific counterparties and pricing are not identified.

    Acquisition Profile

    Mixed occupancy is the most common condition in small two-unit acquisitions and the one most often analysed as a single blended asset. It should not be. The occupied side is an income asset with contractual revenue and constrained access; the vacant side is a repositioning asset with no revenue and unconstrained access. They share a roof, a parcel, and an insurance policy, and almost nothing else in the underwriting.

    Applied exampleSee how this played out in Multifamily Acquisition: Mixed-Occupancy Eightplex, Phoenix — a residential acquisition in Phoenix, AZ.

    Occupied Unit Review

    The occupied side is underwritten from the executed lease: remaining term, rent against submarket comparables, escalation, renewal and holdover provisions, deposit ledger and its handling under Arizona residential landlord-tenant law, and payment history at a summary level. Access for inspection is limited and must be scheduled, so the physical file on this side will be less complete than on the vacant side, and that asymmetry is priced rather than ignored.

    Vacant Unit Review

    The vacant side receives a full inspection. Review covers the condition of interior finishes, appliance presence and condition, the age and performance of the cooling system, which is the dominant mechanical consideration in this market, water heater age, evidence of prior leaks, and any deferred item that would prevent a rental inspection from passing. Achievable rent is set from leased comparables at the finish level the turnover scope will deliver.

    Applied exampleSee how this played out in Selling an Inherited Property in Florida — a residential acquisition in Florida.

    Turnover Scope and Timing

    The vacant side carries a defined make-ready scope and a lease-up interval; the occupied side carries a contingent future turnover whose timing depends on the lease expiration and tenant behaviour. Modelling the two on one timeline shows whether the building's revenue is likely to dip twice, and whether the second turnover can be deliberately sequenced to avoid simultaneous vacancy.

    Operating Expense Review

    Expenses are re-underwritten to post-transfer conditions: Maricopa County property tax, insurance in a market exposed to extreme heat cycles and hail, water and any landscape irrigation cost, cooling-system maintenance reserve set higher than a temperate-market equivalent, and management at two doors. Where the building is on shared service, allocation between an occupied and a vacant unit becomes an immediate accounting question.

    Applied exampleSee how this played out in Cash Offers vs. Traditional Listings: What Sellers Should Know — a residential acquisition in National.

    Basis Analysis

    Basis is the sum of two separately derived unit values, not a blended capitalization of the building's current income. The occupied side is valued on contractual income adjusted toward market at the expiration date; the vacant side is valued on stabilized income less turnover cost and lease-up carry. The sum is then tested against comparable two-unit sales for reasonableness.

    Risk Factors

    The material risks are limited diligence access on the occupied side concealing a condition item, the occupied tenant vacating shortly after closing and converting a partially income-producing asset into a fully vacant one, market rent on the vacant side proving lower than modelled, and cooling-system failure during peak season affecting both revenue and tenant retention.

    Key Decision Points

    The decision turns on whether partial in-place income genuinely reduces risk or merely reduces visibility. Retaining a paying tenant preserves cash flow during the repositioning of the other side, but it also limits inspection, constrains construction scheduling, and may lock a below-market rent in place for the remaining term.

    Key Takeaway

    Different occupancy states create different economic profiles within the same duplex. Each side is underwritten as its own asset, and only then are the two combined into a single acquisition basis.

    Conclusion

    Mixed-occupancy duplexes offer a balance of income continuity and repositioning flexibility, provided the two halves are not averaged into a single misleading figure. The analysis above reflects AceStone Capital Group's approach. Specific properties, counterparties, and pricing are not identified.

    What This Case Shows

    A structured example of how AceStone Capital Group sources, underwrites, and structures off-market residential acquisitions in Phoenix, AZ. For broader context, see our active acquisition markets or initiate a direct-sale review for a similar property.

    Have a Property to Sell?

    Receive a written offer or a clear pass within 1–2 business days.

    Request a Cash Offer