
Back
    Residential Orlando, FL August 2026

    Mixed-Occupancy Distress: When Full Apartments Meet Vacant Retail in Orlando

    A Orlando property with near-full apartments and dark storefronts — separating a temporary lease-up gap from structural commercial weakness.

    This acquisition profile examines asset strategy, underwriting method, transaction structure, and value-creation considerations. Counterparty and pricing details are not disclosed.

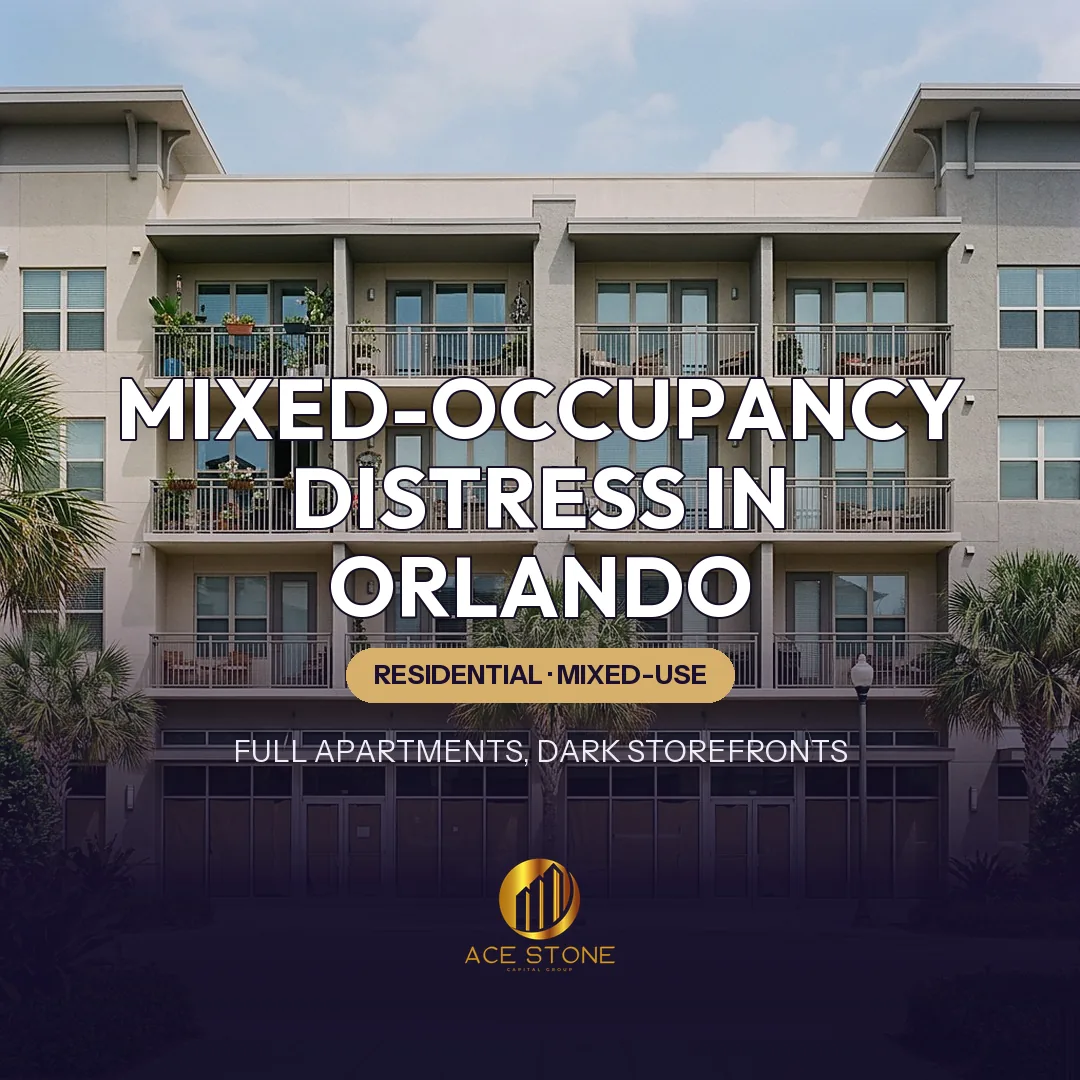
    Orlando mixed-use building with occupied apartment balconies above and several vacant ground-floor storefronts.
    Representative imagery of the asset type and market — not a photograph of the subject property.

    Executive Summary

    Near-full apartments and multiple vacant storefronts in the same building present a specific analytical question: is the retail vacancy a lease-up gap or a verdict? The distinction determines whether the vacant space is upside to be captured or a permanent expense line to be priced. This acquisition profile works through the evidence that separates the two, and models three outcomes rather than assuming the favourable one.

    Case Context

    Specific properties, counterparties, and pricing are not identified. The subject profile is a mixed-use property with apartments above and several ground-floor commercial bays, of which a meaningful share sit dark.

    Applied exampleSee how this played out in Why Out-of-State Owners Sell to Direct Buyers — a residential acquisition in Multi-State.

    The Residential Stream

    The apartments perform: high occupancy, short marketing periods, healthy renewal rates and rents near the achievable band for the submarket. That performance is the reason the asset is financeable at all, and it is also the reason a buyer can afford to be patient about the retail. Residential cash flow after full operating expenses — including the carrying cost of the vacant commercial space — is the first figure calculated.

    Diagnosing the Retail Vacancy

    Temporary vacancy looks like this: recent tenant departures for identifiable business reasons, comparable nearby storefronts leased, active tour activity, and space that is physically deliverable. Structural weakness looks different: multi-year vacancy, several dark bays on the same block, poor visibility or access, bays too shallow or too narrow for current formats, inadequate parking, no delivery access, and rents in the last leases well above what any current tenant would sign. The physical and market evidence is gathered before any lease-up assumption is written.

    Applied exampleSee how this played out in Why Infill Lots Are Outperforming in Growth Corridors — a residential acquisition in U.S. Growth Markets.

    Storefront Configuration

    Configuration determines tenant depth. Frontage width, ceiling height, column spacing, depth-to-frontage ratio, restroom count and location, grease and venting capability, electrical service, ADA access at entry, and signage rights each expand or close off categories of user. A bay that cannot accommodate food service in a submarket where food service is the primary demand driver is not vacant for lack of marketing.

    Cost of Retail Lease-Up

    Filling a bay is not free income. The model carries a marketing period appropriate to the diagnosed condition, a tenant-improvement allowance sized to the likely use, a leasing commission, free rent, and the ongoing carry — taxes, insurance, utilities and common-area cost — during downtime. Where a bay requires a demising wall, a new restroom or a grease line to become leasable, that landlord work is capital, not an expense.

    Applied exampleSee how this played out in The Migration Effect: How Population Shifts Drive Lot Demand — a residential acquisition in U.S. Growth Markets.

    Alternative Commercial Uses

    Where conventional retail demand is absent, alternatives are tested: medical or professional office, service uses, a leasing office or amenity space serving the apartments, storage, or — where zoning permits — conversion of the bays to additional residential units or resident amenity. Converting dark retail into a fitness room, coworking lounge or additional apartments can produce more value than a marginal retail lease, and it removes the recurring re-tenanting cost permanently.

    Scenario One: Conservative

    The vacant bays remain dark for the full underwriting horizon. Income is residential only; the model carries the commercial carrying costs as a permanent drag and includes a modest capital allowance for securing and maintaining the vacant space. This scenario sets the maximum price. If the deal does not work here, it does not work.

    Scenario Two: Base

    One or two bays lease over an extended marketing period at rents below the last contract rents, with full improvement allowances and commissions paid. Residential continues at current performance with normal rent growth. This is the outcome the market most often experiences and the one against which return expectations are set.

    Scenario Three: Successful Lease-Up

    All bays lease within a reasonable window at market rents to credit-acceptable operators. Commercial income is capitalized at a wide rate reflecting new, untested tenancies rather than seasoned ones. This scenario is the return enhancement, never the justification for the price.

    Acquisition Basis and Takeaways

    The price is set on the conservative case, with lease-up treated as unpriced upside. Florida insurance escalation and post-sale tax reassessment are both modelled in every scenario. The core lesson: strong apartments give a buyer the ability to wait out retail vacancy, but only if the purchase price does not already assume the wait ends well.

    What This Case Shows

    A structured example of how AceStone Capital Group sources, underwrites, and structures off-market residential acquisitions in Orlando, FL. For broader context, see our active acquisition markets or initiate a direct-sale review for a similar property.

    Have a Property to Sell?

    Receive a written offer or a clear pass within 1–2 business days.

    Request a Cash Offer