Absentee-Owner Single-Family Acquisition: An As-Is Sale in San Antonio
A analysis of an out-of-state owner selling a San Antonio house as-is, and why a simplified seller experience does not reduce diligence requirements.
This acquisition profile examines asset strategy, underwriting method, transaction structure, and value-creation considerations. Counterparty and pricing details are not disclosed.
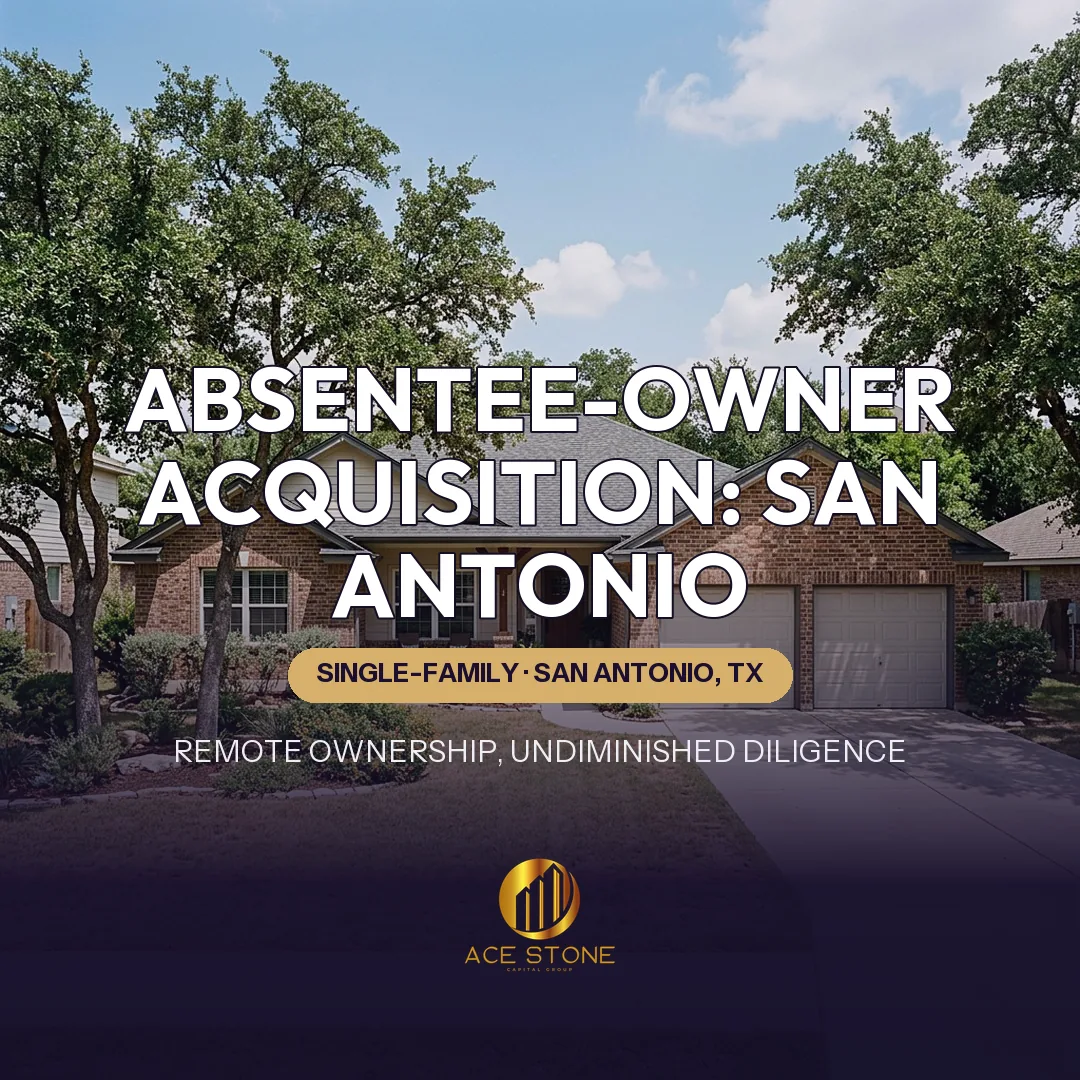
Representative imagery of the asset type and market — not a photograph of the subject property.
Case Context
This acquisition profile examines how AceStone Capital Group underwrites a detached single-family home in the San Antonio market held by an owner residing in another state. Specific properties, counterparties, and pricing are not identified. The subject profile is a single-story brick-and-siding home in an established Bexar County neighborhood, either recently vacated or occupied intermittently, offered without repairs or pre-sale preparation.
Property Profile
The subject is a detached three-bedroom, two-bath house of roughly 1,400 to 1,600 square feet with an attached garage, composition shingle roof, central cooling, and mature shade trees on a standard suburban lot. Texas construction of this profile is typically slab-on-grade, which makes foundation performance and plumbing under slab the two condition items with the widest cost distribution. Tree proximity and soil movement characteristics in parts of the market make differential slab movement a specific rather than a generic concern.
The owner acquired the property through relocation, inheritance, or a prior investment intention and no longer wishes to manage it remotely or prepare it for a conventional listing. The friction being avoided is concrete: coordinating contractors from another state, staging and showings, repair negotiations after inspection, and a financing contingency that can fail late. The owner is optimizing for simplicity and certainty. That preference determines the transaction structure — it does not determine the price, and it does not reduce what must be verified.
Ownership and Title Verification
Because the owner is not local and may not have visited recently, verification precedes valuation. Vesting is confirmed against the recorded deed, and any transfer through probate, divorce decree, or entity ownership is traced to a signer with authority. The title commitment is reviewed for mortgage balances, Texas property tax status and any tax deferral or exemption history, HOA assessments and enforcement liens, judgment liens, mechanic's liens from prior work, and easements or encroachments. Where an entity or estate holds title, authorizing documents are collected before diligence spend continues.
Occupancy status is established directly rather than assumed: vacant, occupied by a family member, occupied by a tenant with or without a written lease, or subject to an unauthorized occupant. Each carries a different closing path. Physical review then covers foundation elevation and evidence of differential movement, roof age and hail-damage history, cooling equipment age and performance in a market where it runs most of the year, supply and drain plumbing under slab, electrical panel type, and moisture at wet walls. A long-unattended house also accumulates pest, landscape, and envelope items that are inexpensive individually and material in aggregate.
Taxes, Utilities and Carry
Carry is confirmed rather than estimated. Bexar County tax status is checked for delinquency, installment arrangements, and whether a homestead or over-65 exemption previously applied and will not survive transfer. Utility accounts are verified as active or disconnected, because a disconnected house cannot be fully inspected and reconnection takes time. Insurance status is checked, since vacancy commonly voids coverage on a standard homeowner's policy and any interim exposure sits with the seller until closing.
Value is set from closed sales of comparable detached homes within the immediate neighborhood, adjusted for living area, lot, garage, roof and mechanical age, and finish level. San Antonio submarkets vary sharply over short distances, so the comparable radius stays tight and school attendance boundaries are respected in selection. As-is comparables — homes that sold without pre-sale repair — are given particular weight, because they reflect the actual buyer pool for the subject in its current condition.
Repair Exposure and Acquisition Basis
Repair exposure is scoped at contracted rates for the work a subsequent owner would actually perform, separated into required items and elective finish items. Basis is then constructed from the as-is value conclusion less required repair scope, less a reserve for unobserved condition where access was limited, less closing and carry cost, less a margin for execution risk. The convenience of the structure — as-is, no repair credits, funding and due-diligence conditions stated in each offer — is delivered through the terms, not funded by an inflated price.
Remote Execution and Closing Logistics
Execution is designed around the owner's absence. Documents are prepared for remote execution using the notarization method the title company and Texas practice accept, with identity verification handled in advance rather than at signing. Proceeds are wired to a pre-verified account with callback confirmation to guard against wire fraud, which is a live risk in remote residential closings. Key handover, lock changes, and any personal-property removal are scheduled explicitly, since the owner will not be present to manage them.
Key Risks
The material risks are foundation movement discovered after limited access, an undisclosed occupant complicating possession, tax or HOA delinquency exceeding the figures presented, wire and identity fraud in a fully remote closing, and roof or mechanical condition worse than a drive-by or photograph suggested. Each is mitigated procedurally where possible and priced where not.
Walk-Away Conditions
The analysis discontinues where signing authority cannot be documented, where possession cannot be delivered clear at closing, where liens and delinquencies exceed a disciplined basis, or where the property cannot be inspected sufficiently to bound foundation and slab-plumbing exposure and the seller will not permit the access required.
Key Takeaways
A simplified seller experience and disciplined property-level underwriting are not in tension. Remote ownership changes the logistics of diligence — scheduling, notarization, funds transfer — and it raises rather than lowers the importance of independent verification, because the owner's own knowledge of current condition is often dated. Owners in this position can review parameters on the residential property acquisitions desk.
Conclusion
Out-of-state owners are frequently well served by a direct as-is structure, provided the counterparty verifies title, occupancy, and condition on its own rather than relying on distance-limited disclosure. The framework above reflects AceStone Capital Group's underwriting posture on assets of this profile.
What This Case Shows
A structured example of how AceStone Capital Group sources, underwrites, and structures off-market residential acquisitions in San Antonio, TX. For broader context, see our active acquisition markets or initiate a direct-sale review for a similar property.
Have a Property to Sell?
Receive a written offer or a clear pass within 1–2 business days.