
Case Context
A modelled analysis of a mixed-use property in a university district: apartments above, food and service retail at grade. Specific properties, counterparties, and pricing are not identified.
A Columbus university-district building where apartment seasonality, unit configuration and food-service retail each behave differently — and must be underwritten that way.
This acquisition profile examines asset strategy, underwriting method, transaction structure, and value-creation considerations. Counterparty and pricing details are not disclosed.
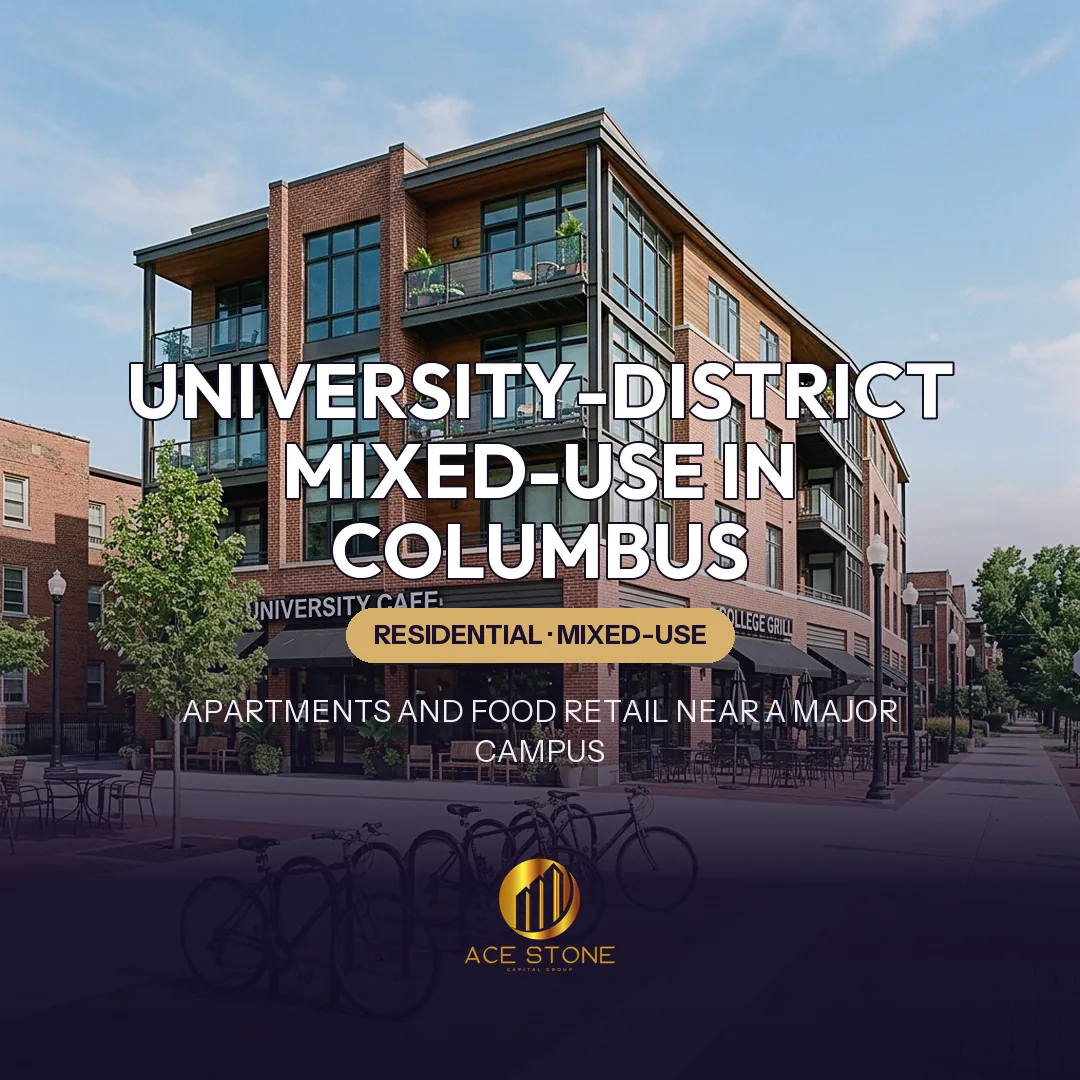
A modelled analysis of a mixed-use property in a university district: apartments above, food and service retail at grade. Specific properties, counterparties, and pricing are not identified.
The residential demand base is a mix of students, graduate students, medical and hospital staff, and young professionals who want walkability. That mix matters more than the headline enrollment number. A building that leases predominantly to undergraduates behaves like a seasonal asset with high turnover and parental guarantees; a building that leases to graduate and staff households behaves closer to conventional apartment stock. The subject sits between the two, and both behaviours are modelled.
Applied exampleSee how this played out in Tenant-Occupied Single-Family Acquisition: Evaluating an Existing Lease in Columbus — a residential acquisition in Columbus, OH.
Leasing in a university district compresses into a short annual window. A unit missed in that window is frequently vacant for the full year rather than for a month, which makes the vacancy factor lumpy rather than smooth. Underwriting reflects the pre-leasing calendar, an all-or-nothing renewal cycle, and the operational requirement to complete unit turns during a narrow summer period at premium labour cost.
Bedroom count drives revenue more than square footage in this submarket. Three- and four-bedroom units let by the bed can outperform larger conventional layouts on gross rent while carrying higher wear, higher turn cost and more intensive management. Configuration also determines exit liquidity: by-the-bed product appeals to a narrower buyer pool. The model prices both the revenue advantage and the narrower exit.
Applied exampleSee how this played out in Selling an Inherited Property in Florida — a residential acquisition in Florida.
Ground-floor food and service uses live on pedestrian traffic that follows the academic calendar. Summer and winter breaks are structural revenue troughs for those operators, which affects their rent-paying capacity and their failure rate. Percentage-rent clauses, if present, are underwritten at conservative sales assumptions. Kitchen infrastructure already installed in a bay is an asset, because it widens the replacement tenant pool and reduces the improvement allowance on the next lease.
Parking supply, permit availability and municipal enforcement shape both streams. Residential tenants in this district frequently do not need a car; retail customers frequently arrive on foot. Where a small lot exists, it is underwritten as a modest amenity rather than a revenue centre, and its maintenance cost is carried in full.
Applied exampleSee how this played out in Cash Offers vs. Traditional Listings: What Sellers Should Know — a residential acquisition in National.
Residential occupancy in a well-located district building is typically high but concentrated in timing; retail vacancy is typically lower-frequency and longer-duration. Rents are set from comparable buildings at similar walking distance from campus, with an explicit adjustment for distance — the rent curve in a university district falls steeply block by block, far more steeply than in a general urban submarket.
The expense model reflects intensive use: higher repairs and maintenance, higher turn costs, more frequent common-area cleaning, pest control, security or access-control systems, and management priced for high-touch student operations rather than conventional apartments. Utilities are examined for metering structure; master-metered buildings in this segment carry real consumption risk. Taxes are restated post-sale and insurance quoted for combined occupancy including food service.
The apartments are capitalized at a rate reflecting a specialized but liquid segment; the retail at a wider rate reflecting calendar-driven tenant risk. Deducted from that value are the deferred maintenance intensity typical of high-turnover buildings, a summer turn budget, and a re-tenanting reserve for each retail bay expiring in the hold period.
The important test is whether the residential component alone supports the basis. If both retail bays go dark and the building operates as apartments with vacant ground-floor space carrying taxes, insurance and utilities, does the asset still cover debt service and hold value? Where the answer is yes, the retail becomes upside rather than dependency. Where it is no, the price is too high regardless of current occupancy.
University-district mixed-use rewards operators who respect the calendar and punishes those who model it as a smooth curve. Underwrite the leasing window, the turn window, the distance curve and the retail trough independently, and require the residential stream to stand alone.
What This Case Shows
A structured example of how AceStone Capital Group sources, underwrites, and structures off-market residential acquisitions in Columbus, OH. For broader context, see our active acquisition markets or initiate a direct-sale review for a similar property.
Receive a written offer or a clear pass within 1–2 business days.
Request a Cash OfferContinue Reading
Additional residential acquisitions structured through the same underwriting and closing framework.