
Back
    Commercial Tampa, FL August 2026

    Vacancy as Opportunity: Repositioning a Mixed-Use Building in Tampa

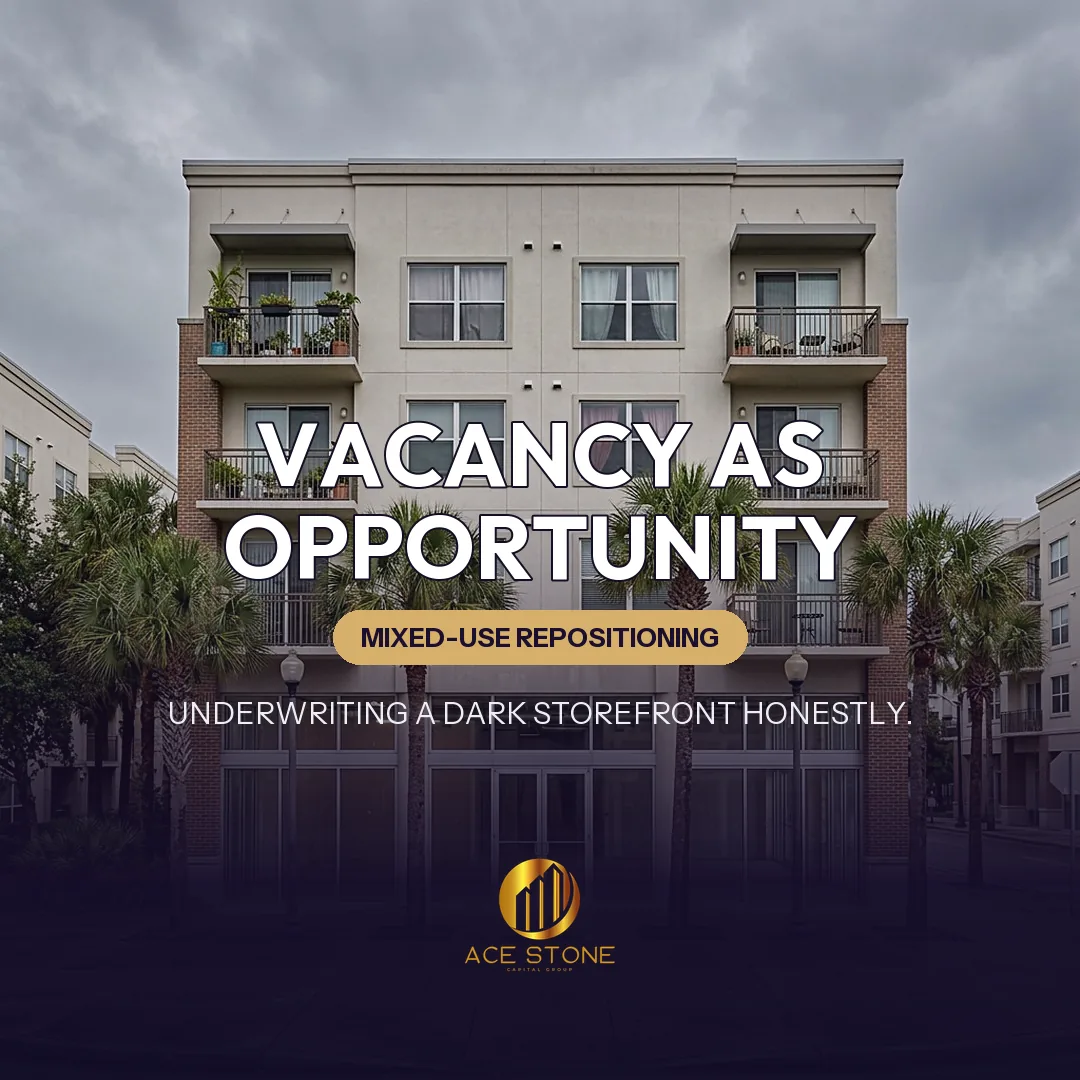
    A Tampa building with stable apartments above and a dark ground-floor storefront — underwritten on today's income, not on a stabilized pro forma.

    This acquisition profile examines asset strategy, underwriting method, transaction structure, and value-creation considerations. Counterparty and pricing details are not disclosed.

    Urban Tampa mixed-use building with occupied apartments above a vacant ground-floor storefront.
    Representative imagery of the asset type and market — not a photograph of the subject property.

    Case Context

    This acquisition profile examines AceStone Capital Group's underwriting method. Specific properties, counterparties, and pricing are not identified. The subject profile is an urban Tampa mixed-use building whose upper residential floors are substantially occupied and paying, while the ground-floor commercial space sits vacant after a prior operator departed. The asset will be offered on a stabilized pro forma. The discipline this case demonstrates is refusing to pay stabilized value for space that has not yet been leased, while still recognizing that the vacancy is the only reason the opportunity exists at all.

    Current Cash Flow Versus Pro Forma

    Two income statements are built. The first is current: residential rents actually being collected, less real operating expenses, with the commercial space contributing nothing and in fact consuming carrying cost through utilities, insurance and taxes on unproductive square footage. The second is stabilized: the same residential income plus a leased commercial component at a supportable market rent. The distance between them is the repositioning value. Price discovery happens in how that distance is shared. The seller's expectation is typically that the buyer pays for the stabilized figure; the underwriting position is that the buyer pays for the current figure plus a risk-adjusted share of what the buyer's own capital and leasing effort will create.

    Applied exampleSee how this played out in Retail Land in Secondary Markets: A Quiet Recovery Story — a commercial acquisition in U.S. Growth Markets.

    Residential Component

    The apartments are reviewed unit by unit: lease terms, rent levels against submarket comparables, delinquency, concessions, tenant tenure, and physical condition including flooring, kitchens, baths and mechanical systems. Tampa's insurance environment and the building's construction type, roof age and window specification are examined explicitly, because insurance cost is a leading driver of net income in this market and a stale premium quote will misstate the entire model. The residential stream is the reason the asset carries itself during lease-up, so its durability is stress-tested before any commercial assumption is entertained.

    Commercial Market Rent and Leasability

    Achievable commercial rent is derived from closed leases in comparable buildings on comparable corridors, not from asking rates. Physical leasability is examined with equal weight: frontage width and visibility, ceiling height, column spacing, depth, rear service access, grease and venting capability, restroom and accessibility compliance, electrical service capacity, and whether the space is deliverable in cold-dark-shell or vanilla-box condition. A space that can only serve a narrow set of uses commands a narrower tenant pool and a longer marketing period, and that is expressed in the model as time, not as a discount to rent.

    Applied exampleSee how this played out in Mixed-Use Development Sites in Live-Work Corridors — a commercial acquisition in U.S. Growth Markets.

    Lease-Up Assumptions

    Conservatism here is not pessimism; it is the difference between a plan and a hope. The model assumes a marketing and negotiation period measured in quarters rather than weeks, a permit and buildout period after signature, and a free-rent period before the first dollar arrives. Tenant improvement allowance is sized per square foot to the condition in which the space will actually be delivered, and leasing commissions are calculated over the full lease term at market rates for both listing and procuring brokers. Carrying costs during the entire period — taxes, insurance, utilities, security — are capitalized into the total cost of stabilization.

    Building Condition and Capital Plan

    Physical diligence covers roof age and remaining life, envelope and window condition, plumbing and electrical service capacity, HVAC across both uses, life-safety and fire separation between commercial and residential occupancies, ADA path of travel, and any code items triggered by a change of use in the ground-floor space. Florida-specific items — wind mitigation features, roof attachment documentation, prior water intrusion history — are examined because they influence insurability and premium as much as they influence repair budget. Each finding becomes a line in a capital plan with a cost and a timing, not an unquantified caveat.

    Applied exampleSee how this played out in The Value of Entitled Commercial Land in Tight Credit Cycles — a commercial acquisition in U.S. Growth Markets.

    Acquisition Basis

    The basis is anchored to residential net income capitalized at a market residential rate, plus the commercial space valued at a discount to its stabilized contribution, less the full cost of stabilization including tenant improvement, commissions, downtime and carrying cost, less the capital plan, less a required return for taking leasing risk that the seller was unwilling to take. Stated plainly: the vacant square footage is bought closer to its as-is condition than to its future potential, because the future potential is the buyer's work product.

    Downside Scenario

    The downside case assumes the commercial space remains unleased for the full projected hold, or leases at a materially lower rent to a weaker credit after an extended marketing period. Under that scenario the question is whether residential income alone covers debt service, taxes, insurance and reserves with margin. If it does, the commercial component is genuine optionality and the position is survivable. If it does not, the acquisition depends on a leasing outcome nobody controls, and the correct decision is a lower price or no transaction.

    Exit Positioning and Takeaways

    Once the ground floor is leased to a credible operator on a multi-year term, the asset presents to the market as a stabilized mixed-use property with a demonstrable income history rather than a project. That transformation — from story to statement — is the source of value creation here, and it is created by execution rather than by market movement. The core lesson generalizes to every partially vacant hybrid asset: stabilized value belongs to whoever funds and delivers the stabilization, and paying for it in advance transfers the return to the seller.

    What This Case Shows

    A structured example of how AceStone Capital Group sources, underwrites, and structures off-market commercial acquisitions in Tampa, FL. For broader context, see our active acquisition markets or initiate a direct-sale review for a similar property.

    Have a Property to Sell?

    Receive a written offer or a clear pass within 1–2 business days.

    Request a Cash Offer