
Back
    Commercial Tampa, FL August 2026

    Small-Bay Office Portfolio: Acquiring Five Professional Buildings Across Tampa

    Five Tampa professional office buildings evaluated as one acquisition — does a fragmented rent roll earn a diversification premium or a complexity discount?

    This acquisition profile examines asset strategy, underwriting method, transaction structure, and value-creation considerations. Counterparty and pricing details are not disclosed.

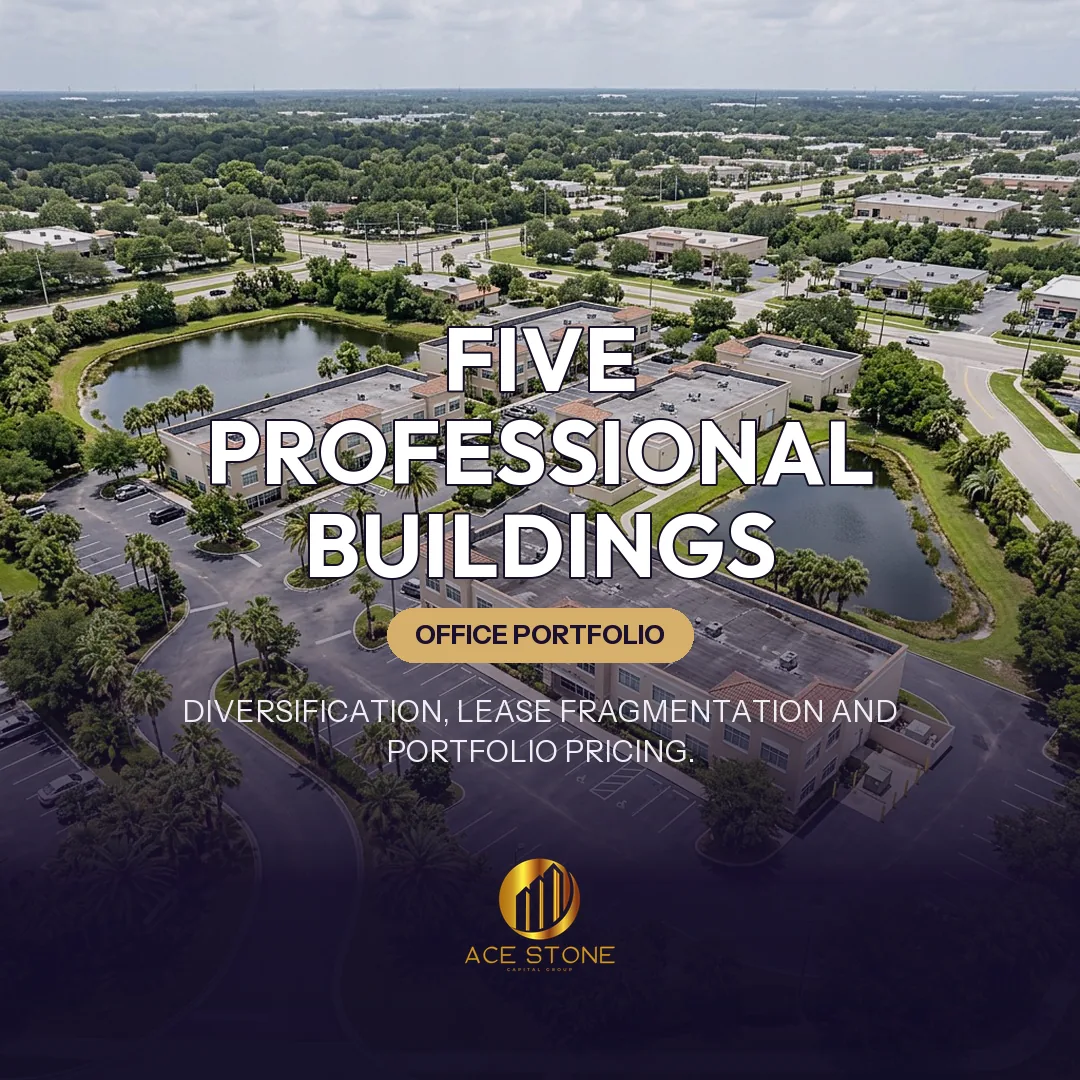
    Tampa suburban office park with several small professional buildings.
    Representative imagery of the asset type and market — not a photograph of the subject property.

    Case Context

    This acquisition profile examines AceStone Capital Group's underwriting method. Specific properties, counterparties, and pricing are not identified. The subject profile is five small professional office buildings across suburban Tampa nodes, ranging from roughly eight to twenty thousand square feet each, collectively housing several dozen tenancies: accountants, attorneys, insurance agencies, therapists, small engineering practices and back-office users. The seller wishes to trade the group as one package. The question is whether the portfolio is worth more, the same, or less than the sum of its buildings.

    Building-Level Underwriting First

    Portfolio pricing is meaningless until each asset is underwritten independently. Every building receives its own rent roll abstraction, occupancy history, expense reconstruction with a post-sale tax reassessment, condition survey with a dated capital plan, submarket rent comparison and standalone valuation. Only when five separate values exist can a portfolio conclusion be drawn. This sequence also protects against the classic package structure in which two strong assets carry three weak ones and the blended yield conceals which buildings actually produce the income.

    Applied exampleSee how this played out in Retail Land in Secondary Markets: A Quiet Recovery Story — a commercial acquisition in U.S. Growth Markets.

    Lease Fragmentation

    Dozens of small leases behave statistically rather than individually. Any single departure is immaterial; the aggregate turnover rate is not. The analysis measures the weighted average lease term across the portfolio, the distribution of expirations by year and by building, average tenancy size, historical renewal rates and the concentration of any one tenant within a single building. Fragmentation is genuinely protective — no tenant can impair the portfolio — but it also means the owner is permanently in the leasing business, with a steady annual requirement for improvement dollars, commissions and downtime that must be reserved rather than treated as episodic.

    Management Intensity

    Small-bay office is management-heavy per dollar of income. Five separate properties mean five roofs, five parking lots, five sets of vendor contracts, five insurance schedules, five tax parcels and five sets of building-level tenant relationships, plus a leasing programme that must fill small suites continuously. Management fees are modelled at the rate this workload actually costs, not at the rate a single large asset would carry, and an on-site or roving maintenance resource is priced explicitly. Understating this line is the most common way portfolios of this type miss their underwriting.

    Applied exampleSee how this played out in Mixed-Use Development Sites in Live-Work Corridors — a commercial acquisition in U.S. Growth Markets.

    Tenant Profile and Credit

    Professional-services tenants of this size rarely provide audited financials. Credit assessment therefore relies on payment history, tenure, guarantee structure, security deposits, the nature of the practice and the tenant's own investment in its suite. The mix is examined for hidden correlation: several tenants dependent on the same industry, or on a single nearby institution, are less diversified than a tenant count suggests. Small tenants also tend to be sensitive to local economic conditions, so the portfolio's income is modelled with a credit-loss factor rather than assumed full collection.

    Geographic Concentration and Submarket Exposure

    Five buildings within one metro are diversified against tenant risk but not against submarket risk. The analysis maps each asset's node, the employment base it serves, competing supply within a short drive, and exposure to shared local factors — flood zone and windstorm insurance conditions relevant to the Gulf coast, planned road or transit changes, and the direction of nearby development. Where two or three assets sit in the same corridor, the portfolio's effective diversification is lower than the property count implies, and pricing should reflect that.

    Applied exampleSee how this played out in The Value of Entitled Commercial Land in Tight Credit Cycles — a commercial acquisition in U.S. Growth Markets.

    Portfolio NOI Versus Property NOI

    Aggregate net operating income is built by summing normalized property-level figures and then applying portfolio-level adjustments: a management structure priced for five assets, a shared reserve for annual small-suite turnover, insurance quoted as a schedule rather than five individual policies, and any cost efficiency from common vendors. Efficiencies are real but modest, and they are only credited where a specific mechanism exists. Portfolio-level costs that do not appear at property level — asset management, accounting across five entities, financing administration — are added rather than ignored.

    Premium, Parity or Discount

    Three pricing conclusions are tested. A premium is warranted where the group offers genuine scale in a market where individual assets of this size are hard to source, where the rent roll is well staggered and where the buildings are physically sound. Parity is the common answer: the diversification benefit and the management burden roughly offset. A discount is appropriate where the package forces the buyer to accept one or two assets it would not buy alone, where capital plans are concentrated in the same period, or where the seller is using the portfolio structure to clear a problem building. In this profile the analysis leans toward parity with an explicit reserve for management intensity.

    Structure, Financing and Disposition Optionality

    Structure matters as much as price. Allocating a defensible purchase price to each parcel supports later individual financing, individual sale and clean tax treatment, and it gives the buyer the option to reprice or remove an asset if diligence reveals a defect. Financing may be portfolio-level for efficiency or asset-level for flexibility; cross-collateralization increases leverage capacity but removes the ability to sell one building without a release provision. Because the exit for these assets can be either a package sale to another private investor or a series of individual sales — including to owner-users — retaining the ability to unbundle is worth real money.

    Key Takeaways

    Underwrite five buildings, then decide whether the package changes the answer. Fragmented leases protect income but guarantee continuous leasing cost; five properties in one metro diversify tenants, not the submarket; and management intensity is the line item that decides whether the portfolio performs. Price to the sum of defensible property values, allocate deliberately, and preserve the option to sell them one at a time. Owners considering a coordinated exit can review the firm's portfolio acquisition parameters.

    What This Case Shows

    A structured example of how AceStone Capital Group sources, underwrites, and structures off-market commercial acquisitions in Tampa, FL. For broader context, see our active acquisition markets or initiate a direct-sale review for a similar property.

    Have a Property to Sell?

    Receive a written offer or a clear pass within 1–2 business days.

    Request a Cash Offer