
Back
    Commercial Atlanta, GA August 2026

    From Functional Obsolescence to Creative Office: Repositioning an Atlanta Asset

    A Atlanta infill loft building tested against a creative-office repositioning — does the rent premium actually pay for the capital?

    This acquisition profile examines asset strategy, underwriting method, transaction structure, and value-creation considerations. Counterparty and pricing details are not disclosed.

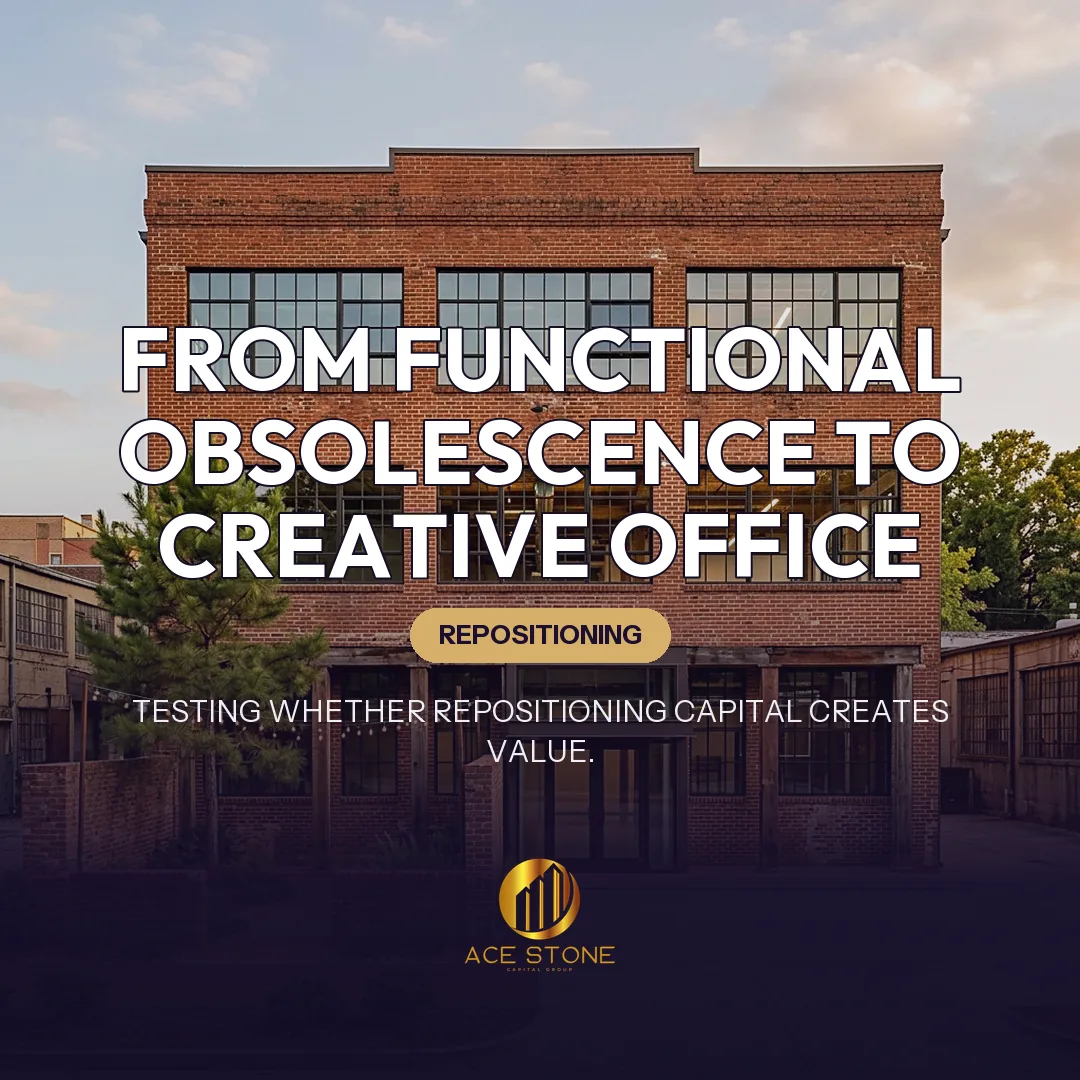
    Atlanta brick loft building converted to creative office.
    Representative imagery of the asset type and market — not a photograph of the subject property.

    Case Context

    This acquisition profile sets out AceStone Capital Group's repositioning method. Specific properties, counterparties, and pricing are not identified. The subject profile is an older two-storey masonry office and light-industrial building in an Atlanta infill neighbourhood: high bays, timber or steel structure, generous window openings, dated finishes, weak curb presentation and below-market occupancy. The physical DNA fits the creative-office format. The analytical discipline is to prove that the achievable rent premium and occupancy improvement exceed the cost of achieving them, rather than assuming that exposed brick creates value.

    What Makes a Building a Candidate

    Creative-office demand is driven by attributes that cannot be manufactured cheaply: floor-to-structure height that permits exposed services and mezzanines, deep natural light from large openings on more than one elevation, column-free or wide-bay spans that allow open plans, structural character worth revealing, ground-level access, and a neighbourhood context tenants want to be in. The subject is scored on each. Buildings that lack the height or the window line cannot be renovated into the format; a cosmetic refresh in a conventional low-ceiling office building produces a refreshed conventional office building, at conventional office rent.

    Applied exampleSee how this played out in Why Industrial Land Is the New Core Asset — a commercial acquisition in U.S. Growth Markets.

    Target Tenant Demand

    The demand pool is defined specifically rather than aspirationally: design and architecture practices, marketing and media firms, software and product teams, post-production and content studios, showroom-and-office hybrid users, and professional firms seeking a differentiated identity. Each of these has a size profile, a parking expectation, an amenity expectation and a tolerance for rent. The analysis tests how many such requirements have actually transacted in the immediate submarket over recent years and at what effective rents, because a repositioning that depends on demand migrating from another neighbourhood is a marketing plan, not an underwriting assumption.

    Scope and Cost of the Repositioning

    The capital plan is scoped in tiers. Base building work covers roof, envelope and sealant, window replacement or restoration, structural repair, new mechanical, electrical and plumbing capacity, fire protection, and code and accessibility upgrades. Repositioning work covers the entry sequence and lobby, corridor and restroom finishes, exposure of structure and services, exterior treatment and signage, landscaping, an outdoor terrace or courtyard, bicycle and end-of-trip facilities, and parking-lot rehabilitation. Tenant improvements are budgeted separately at the level this tenant type expects, along with contingency sized for the surprises that older buildings reliably deliver once walls are opened.

    Applied exampleSee how this played out in Retail Land in Secondary Markets: A Quiet Recovery Story — a commercial acquisition in U.S. Growth Markets.

    Rent Premium Testing

    The central test compares two forward positions for the same building. The unrenovated position holds current rents, current occupancy and a modest capital budget. The renovated position applies the target creative-office rent, higher stabilized occupancy and the full capital plan. The difference in stabilized net operating income is then measured against the incremental capital spent. If the incremental yield on that capital does not clear the return required for construction and lease-up risk — with a margin, not marginally — the repositioning destroys value even if the finished building looks better. Rent premiums are drawn from signed comparable leases net of concessions, not from asking rates.

    Lease-Up Timing and Carry

    Repositioning takes the building partially or fully offline. The model schedules construction duration, permitting time, the displacement or relocation of any existing tenants, and a lease-up curve that begins during or after completion. Throughout that period the owner carries taxes, insurance, utilities, security and debt service with reduced income. Extended timelines are the most common source of underperformance in this strategy, so the base case uses a realistic rather than optimistic schedule and the downside case adds meaningful delay.

    Applied exampleSee how this played out in Mixed-Use Development Sites in Live-Work Corridors — a commercial acquisition in U.S. Growth Markets.

    Parking and Amenity Reality

    Infill creative-office tenants tolerate lower parking ratios than suburban users but do not ignore parking. The analysis counts actual available stalls, tests whether adjacent land or shared arrangements can supplement supply, and considers transit and cycling access honestly rather than as a substitute. Amenity expectations — gathering space, outdoor area, showers, secure bike storage, good coffee within walking distance — are treated as leasing requirements with capital costs attached, because their absence shows up as longer downtime rather than as lower rent.

    Risk Register

    The principal risks are cost overrun in an older structure, schedule slippage through permitting and long-lead equipment, a thinner tenant pool than assumed, concession creep that erodes effective rent, neighbourhood change that arrives later than projected, and capitalization-rate movement between acquisition and exit. Each is assigned a downside case. The plan is judged on whether it survives two adverse variables occurring together — for example, a cost overrun plus a slower lease-up — because that combination is more common than any single failure.

    Exit Valuation

    The exit assumes a stabilized asset sold to a private or regional investor familiar with the format, at a capitalization rate at or slightly above entry, applied to conservatively stabilized income. Value creation is measured as stabilized value less total project cost, and that spread must be wide enough to compensate for the risk taken. Where the spread is thin, the correct decision is either a lower acquisition basis or a narrower scope that spends less capital and accepts a smaller rent improvement.

    Key Takeaways

    Repositioning creates value only when the building's physical attributes support the format, the local demand pool is demonstrable, and the incremental rent clears the incremental capital with room to spare. Aesthetics are not a strategy. Scope the base building before the finishes, price the carry, and let the yield-on-cost calculation — not the rendering — make the decision. Owners of comparable Atlanta assets can review the firm's acquisition and repositioning criteria.

    What This Case Shows

    A structured example of how AceStone Capital Group sources, underwrites, and structures off-market commercial acquisitions in Atlanta, GA. For broader context, see our active acquisition markets or initiate a direct-sale review for a similar property.

    Have a Property to Sell?

    Receive a written offer or a clear pass within 1–2 business days.

    Request a Cash Offer