Industrial Portfolio Acquisition: Seven Small-Bay Warehouses Across Atlanta
A seven-property small-bay industrial portfolio in Atlanta, underwritten asset by asset before any portfolio-level conclusion is permitted.
This acquisition profile examines asset strategy, underwriting method, transaction structure, and value-creation considerations. Counterparty and pricing details are not disclosed.
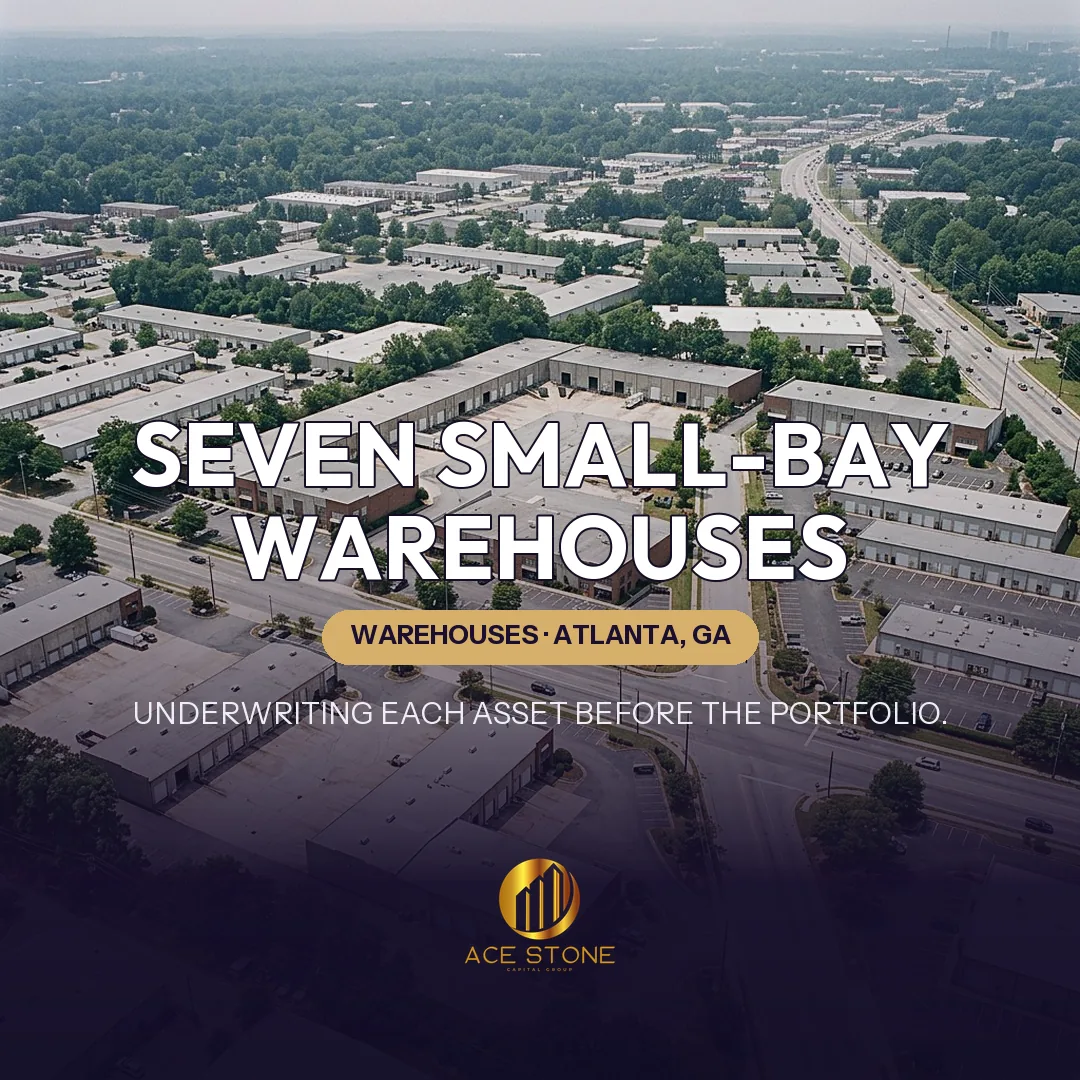
Representative imagery of the asset type and market — not a photograph of the subject property.
Case Context
This acquisition profile examines AceStone Capital Group's underwriting method for an asset of this type. Specific properties, counterparties, and pricing are not identified. The subject profile is a seven-property small-bay industrial portfolio distributed across several Atlanta submarkets, offered as a single package on blended portfolio metrics.
Executive Summary
Portfolios are marketed on blended statistics, and blended statistics conceal dispersion. The method here is to underwrite each of the seven assets as a standalone acquisition, assign each a standalone value, and only then ask what aggregation is worth. In this profile the blended occupancy and blended rent gap look attractive; the asset-level work shows that a small number of buildings carry most of the value and a small number carry most of the risk.
The seven assets vary by vintage, size, submarket and configuration: several well-located multi-tenant small-bay parks with strong occupancy histories, two mid-quality buildings with adequate loading but dated finishes and lower rents, and one asset with persistent occupancy problems in a weaker location. Total square footage is concentrated in the larger three, but net operating income is concentrated in the two strongest — an asymmetry the blended presentation does not surface.
Asset-Level Underwriting Method
Each property is analysed on the same schedule: unit mix and size, occupancy history over several years rather than at a single point, tenant roster and concentration, in-place rent versus market rent per unit, lease expiration schedule, building condition including roof, pavement, dock and roll-up doors, power and lighting, site circulation, submarket quality, and the capital required to bring the asset to a competitive standard. Each then receives a standalone value and a standalone risk rating.
The two strongest properties are well-located small-bay parks with high historical occupancy, short average lease terms and a waiting list of local users. Short terms are an advantage here: they allow rents to be marked to market progressively without a single large exposure. These assets support the tightest capitalization rates in the portfolio, would sell individually with the deepest buyer pool, and are the reason the package is attractive at all.
The Middle Assets
Three properties sit in the middle: functional buildings with acceptable locations, occupancy in a normal range, rents modestly below market and deferred maintenance that is visible but not structural. Each carries a defined capital programme — roof sections, pavement, lighting, dock door replacement and signage — with a corresponding rent uplift. These are conventional value-add assets and are underwritten as such, with capital funded at closing and rent uplift lagging the spend.
Two properties fail on their own terms. One suffers chronic vacancy driven by a location that lost its logic when nearby uses changed, along with a bay depth that suits few users. The other has adequate physical characteristics but a tenant roster dominated by a small number of related businesses, creating a concentration exposure inconsistent with the diversification the portfolio is meant to provide. Both are valued at prices reflecting extended lease-up and elevated capital, which is well below the blended metric implies.
Tenant Diversification and Rollover
Aggregated across the portfolio, tenancy comprises a large number of local contractors, tradespeople, service businesses and small distributors — genuine diversification of credit. Rollover is examined by year and by property rather than in aggregate: a portfolio with smooth blended rollover can still contain a single asset with most of its income expiring in one twelve-month window, and that concentration is where the risk actually sits.
Operating Expenses and Management Intensity
Small-bay industrial carries higher management intensity than single-tenant distribution: more leases, more renewals, more collections, more service calls, more turnover of small units. Expenses are modelled with realistic staffing or third-party management costs, higher repairs and maintenance per square foot, higher bad debt, and reassessed property taxes at the allocated purchase price for each asset. Seven properties across multiple submarkets also carry a coordination cost that a single-asset model omits.
Capital Expenditure Exposure
Capital is scheduled property by property and item by item — roofs by remaining life, pavement by condition, dock equipment, roll-up doors, lighting retrofits, fire protection, and site drainage. Aggregated, the portfolio's capital requirement is substantially larger than any single-asset transaction of similar value would present, and it is front-loaded because deferred maintenance across seven buildings does not wait its turn politely.
Portfolio Premium, Parity or Discount
Aggregation earns a premium when it delivers scale that a buyer cannot easily assemble, operating leverage across a single management platform, and diversification of income. It earns a discount when it forces a buyer to accept assets they would not buy individually, when the weakest properties would trade below the blended metric in the individual market, and when a future exit requires either selling the package to a similarly constrained buyer or breaking it up at cost. In this profile, with two genuinely weak assets, the correct conclusion is a discount to the sum of standalone values.
Scenario and Sensitivity Analysis
Three portfolio scenarios are modelled: acquire all seven at a blended price supported by the sum of standalone values less an aggregation discount; acquire the five viable assets at their standalone values if the seller will divide; and acquire all seven with the two weak assets underwritten at land-and-shell value and earmarked for disposition. Each is flexed for lease-up duration on the weak assets, capital overrun and exit capitalization rate dispersion between strong and weak properties.
Exit Strategy
Exit is modelled two ways. A single portfolio sale is efficient but narrows the buyer pool and reintroduces the same blended-metric discount at the other end. A staged individual disposition typically realizes more value in aggregate, because the strongest small-bay assets attract deep local and private-buyer demand, but it takes longer and carries repeated transaction costs. The likely exit path is decided before entry, because it changes what the portfolio is worth today.
Acquisition Decision
On these underwriting assumptions the portfolio is acquirable at the sum of asset-level values less a discount for the two impaired properties and for the front-loaded capital programme, with capital reserved at closing and a defined disposition plan for the weak assets. Paying the blended asking metric would mean buying the two problem buildings at the price of the two best ones.
Key Takeaways
Never underwrite a portfolio as an average. Value each asset as though it were the only one on offer, identify where income and risk are actually concentrated, price the aggregate capital programme honestly, and decide whether aggregation is worth a premium or a discount on evidence rather than convention.
What This Case Shows
A structured example of how AceStone Capital Group sources, underwrites, and structures off-market commercial acquisitions in Atlanta, GA. For broader context, see our active acquisition markets or initiate a direct-sale review for a similar property.
Have a Property to Sell?
Receive a written offer or a clear pass within 1–2 business days.